


See liquidity more clearly in real time.
Compare plans to access deeper market visibility for liquidity.
Education
September 5, 2025
Updated
Trade Like an Institutional Trader: How to Read the Market Like the Pros
Institutional traders have one major advantage over retail traders: deep liquidity access and order execution strategies that reduce market impact. Unlike retail traders placing small positions, institutional players manage massive order sizes—often thousands of contracts at a time. But trading in large size isn’t as simple as clicking “buy” or “sell.”
The key to trading like an institution is understanding how liquidity interacts with price movement and learning how to position yourself alongside big money instead of against it.
What Is Institutional Trading?
Institutional trading refers to the way professional firms such as banks, hedge funds, and asset managers participate in financial markets. These participants trade large position sizes and must carefully manage execution, liquidity access, and market impact. Instead of reacting to indicators, institutional traders focus on how liquidity forms, shifts, and absorbs volume across key price levels.
Understanding institutional trading helps explain why price often reacts sharply at certain levels and why markets frequently move before obvious technical signals appear.
In this guide, we’ll break down how institutions execute trades, how liquidity influences market moves, and how retail traders can use Bookmap to gain similar insights.
📌 What You’ll Learn
- How institutions manage liquidity and order execution
- Why understanding liquidity zones and market absorption is critical
- How retail traders can use Bookmap’s tools to track institutional activity
🔗 Want to see institutional order flow in action? Compare Bookmap Plans Here
Table of Contents
- What Is Institutional Trading?
- Who Are Institutional Traders?
- How Institutional Traders Think About Liquidity
- Identifying Institutional Liquidity Zones
- How Institutional Traders Execute Large Orders
- VWAP, TWAP & Institutional Order Execution Strategies
- Dark Pools, Block Trades & Alternative Trading Systems
- How Liquidity, Slippage & Market Impact Affect Institutional Trades
- Institutional Trading vs. Retail Trading
- How to Identify Institutional Trading Activity
- Volume, Order Flow & Footprint Charts for Institutional Activity
- Smart Money Concepts: Order Blocks & Liquidity Sweeps
- Wyckoff Accumulation and Distribution Explained
- How Institutions Execute Trades Without Moving the Market
- Institutional Trading and Market Structure
- Trading Alongside Institutional Players: Key Strategies
- Common Institutional Trading Strategies
- How to Track Institutional Holdings & 13F Filings
- Common Myths About Institutional and Smart Money Trading
- Conclusion
- FAQ
Who Are Institutional Traders?
“Institutional trader” covers several distinct types of firms, each with different objectives but similar execution constraints:
- Banks — trading for their own account (proprietary desks) and on behalf of clients, often the largest source of market-making liquidity.
- Hedge funds — managing pooled capital with a wide range of strategies, from short-term liquidity-driven trading to long-term positioning.
- Asset managers — running mutual funds, ETFs, and separately managed accounts, generally trading on longer time horizons tied to portfolio construction rather than short-term price moves.
- Pension funds — managing long-term retirement capital, typically the slowest-moving and most risk-averse of the group.
- Proprietary trading firms — trading firm capital directly, often on shorter time horizons with a heavier focus on execution speed and market microstructure.
Despite different mandates, all of them share the same core problem covered throughout this guide: moving large size without moving the market against themselves.
How Liquidity, Slippage & Market Impact Affect Institutional Trades
Liquidity is the foundation of every institutional trade. Unlike retail traders who can buy or sell 100 shares at market without moving price, institutions must be highly strategic about their execution.
Why Liquidity Matters
- Institutions execute thousands of contracts at a time. If they enter a trade at market price, they could push price against themselves before filling their position.
- They need liquidity providers on the other side—if they’re buying, they need a large pool of sellers at a key level.
- If liquidity is weak or unstable, price will move erratically, increasing execution costs.
How Institutions Use Liquidity to Their Advantage
Institutions don’t chase price. Instead, they target liquidity zones where large orders exist, allowing them to enter positions without causing massive price slippage.
Example:
An institutional trader wants to buy 1,000 NASDAQ futures contracts. Instead of buying at market, they wait for liquidity to appear on the heatmap, indicating where sellers are willing to absorb large orders.
Two related but distinct costs drive institutional execution decisions: slippage is the difference between the price an order was expected to fill at and the price it actually filled at, and market impact is the degree to which the act of placing the order itself moved the price against the trader. Slippage can happen even with zero market impact, in a fast-moving market; market impact is specifically the cost of a trader’s own size being large relative to available liquidity. Every execution strategy covered in this guide — iceberg orders, VWAP/TWAP, dark pools — exists specifically to manage market impact, since it’s the cost most directly within an institution’s control.
Identifying Institutional Liquidity Zones
Institutional liquidity zones form where large participants repeatedly transact or defend price. These areas often emerge as zones where price pauses, consolidates, or reacts multiple times. Institutions use these zones to accumulate or distribute positions without forcing price to move aggressively against them.
By observing how liquidity behaves as price approaches these levels, traders can assess whether institutions are absorbing volume, withdrawing liquidity, or allowing price to move freely.
Institutional Trading vs. Retail Trading
| Institutional Trading | Retail Trading | |
|---|---|---|
| Typical order size | Thousands of contracts / shares | Single-digit to low hundreds |
| Primary constraint | Market impact and execution cost | Capital and risk management |
| Execution method | Algorithmic (VWAP/TWAP, iceberg, dark pool) | Manual or simple automated orders |
| Time horizon | Varies widely by firm type | Often shorter, more reactive |
| Market visibility | Some activity intentionally hidden (dark pools, icebergs) | Fully visible on the public order book |
| Main edge | Capital, information, execution technology | Speed of decision-making, flexibility |
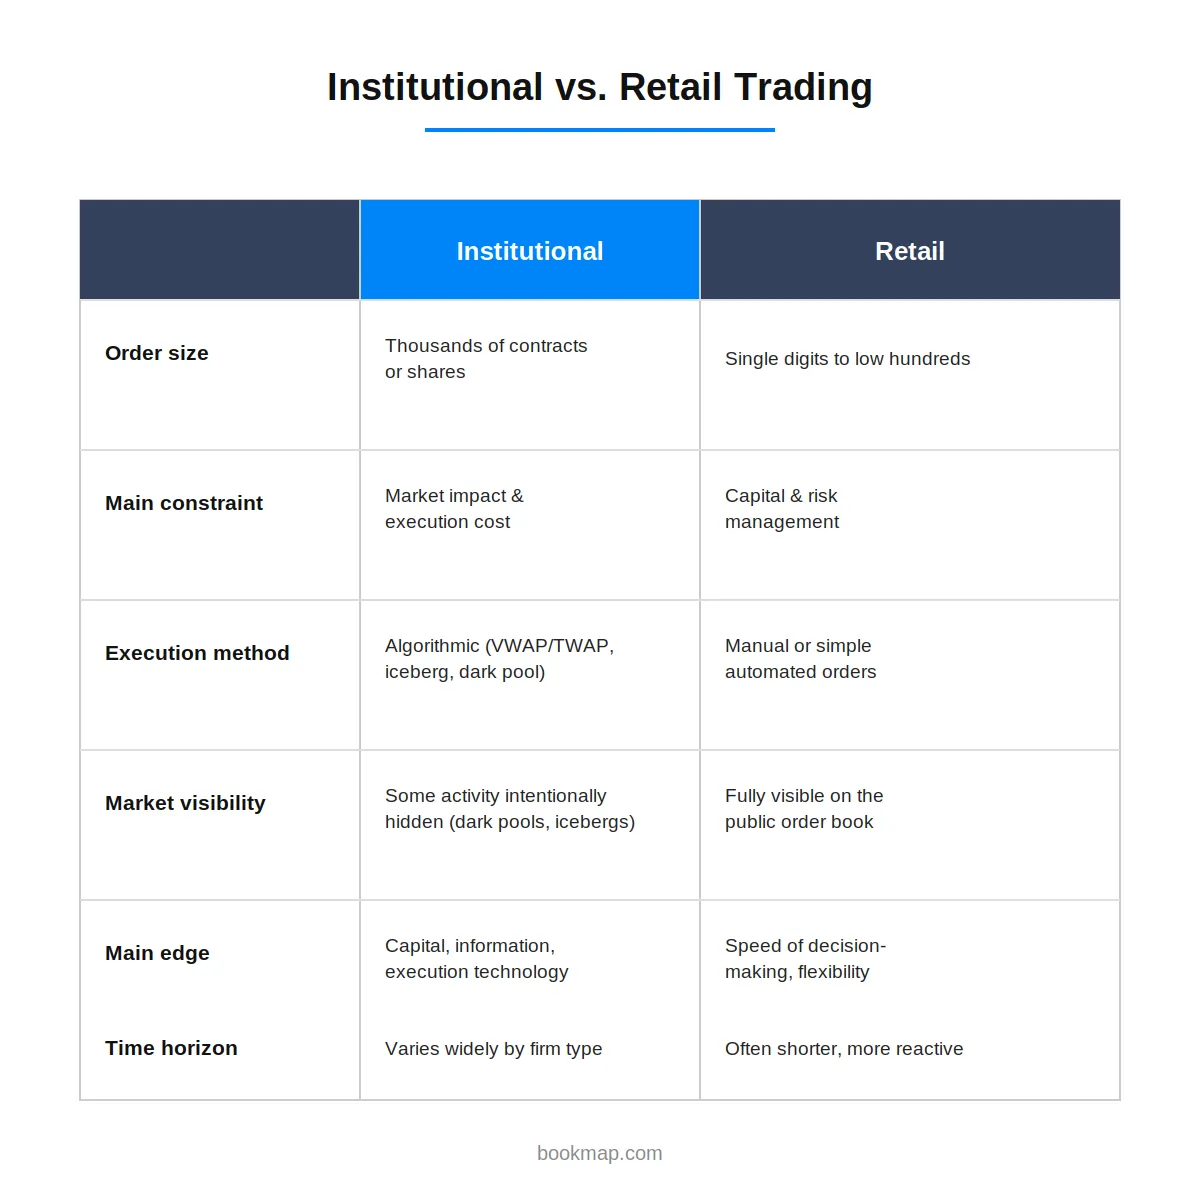
Neither side has an unconditional advantage — institutions manage size that would be impossible for a retail account to move without destroying their own price, while retail traders can enter and exit instantly without needing to manage market impact at all. Retail traders reading order flow are effectively trying to see the traces institutional size leaves behind, covered throughout the rest of this guide. For more on what actually separates consistently profitable retail traders from everyone else, see Bookmap’s piece on how long it takes to become a profitable trader.
The Role of the Order Book & Level 2 Data
Before Bookmap and modern visualization tools, institutional traders had to rely on Level 2 order books to estimate where liquidity was sitting. But raw order book data is limited—many orders are pulled before they ever execute, making it difficult to trust what’s real.
How to Identify Institutional Trading Activity
Beyond the liquidity-zone behavior covered earlier, a few specific signals tend to indicate institutional participation rather than broad retail activity:
- Repeated absorption at a level — price testing the same level multiple times without breaking it, suggesting a large passive order absorbing aggression rather than the level simply holding by chance.
- Consistent order sizing at regular intervals — a signature of algorithmic execution (VWAP/TWAP) rather than discretionary, irregular retail order flow.
- Sudden depth changes disconnected from news — large size appearing or disappearing from the book without any corresponding headline, often institutional positioning rather than a retail reaction to information.
- Price behavior inconsistent with visible order size — a level holding despite what looks like thin visible liquidity is a common iceberg-order tell, covered earlier in this guide.
None of these signals is conclusive alone; institutional activity is generally inferred from a pattern across several of them together, not confirmed from a single observation.
Volume, Order Flow & Footprint Charts for Institutional Activity
A footprint chart displays buy and sell volume at each price level within a given candle, rather than showing only the candle’s open, high, low, and close — making it possible to see whether a candle’s move was driven by aggressive buying or aggressive selling, and where within that price range the actual volume was concentrated. This is a useful complement to a liquidity heatmap: the heatmap shows resting orders, while a footprint chart shows executed volume, and reading both together gives a fuller picture of institutional participation at a given level than either alone.
For a deeper look at using order flow visualization specifically to spot this kind of activity, see Bookmap’s deep dive into order flow and liquidity analysis.
Smart Money Concepts: Order Blocks & Liquidity Sweeps
“Smart money concepts” (SMC) is a popular retail trading framework built around inferring institutional activity from candlestick patterns. Liquidity sweeps — price pushing through a visible high or low specifically to trigger resting stop orders before reversing — are already covered in this guide under “Understand Market Sweeps & Trapped Traders” above. Order blocks, the other core SMC concept, refer to a candle or cluster of candles just before a strong move, theorized to mark where institutional orders were placed.
Order blocks are covered in full depth, including how they compare to genuine order-book data, in Bookmap’s guide to market structure — worth reading alongside this guide, since the same distinction (a pattern-based inference versus an actual observed order) applies directly to how much weight to put on any SMC concept when trading.
Wyckoff Accumulation and Distribution Explained
Richard Wyckoff’s market cycle model, developed in the early 20th century, describes four phases institutions are theorized to move through when building or unwinding a large position:
- Accumulation — informed buying while price is range-bound and sentiment is weak, building a position quietly before a move.
- Markup — the resulting uptrend, as the accumulated position (plus new buying) pushes price higher.
- Distribution — the same participants unwinding their position into strength, often while price still appears to be making new highs.
- Markdown — the resulting downtrend, as distribution completes and selling pressure takes over.
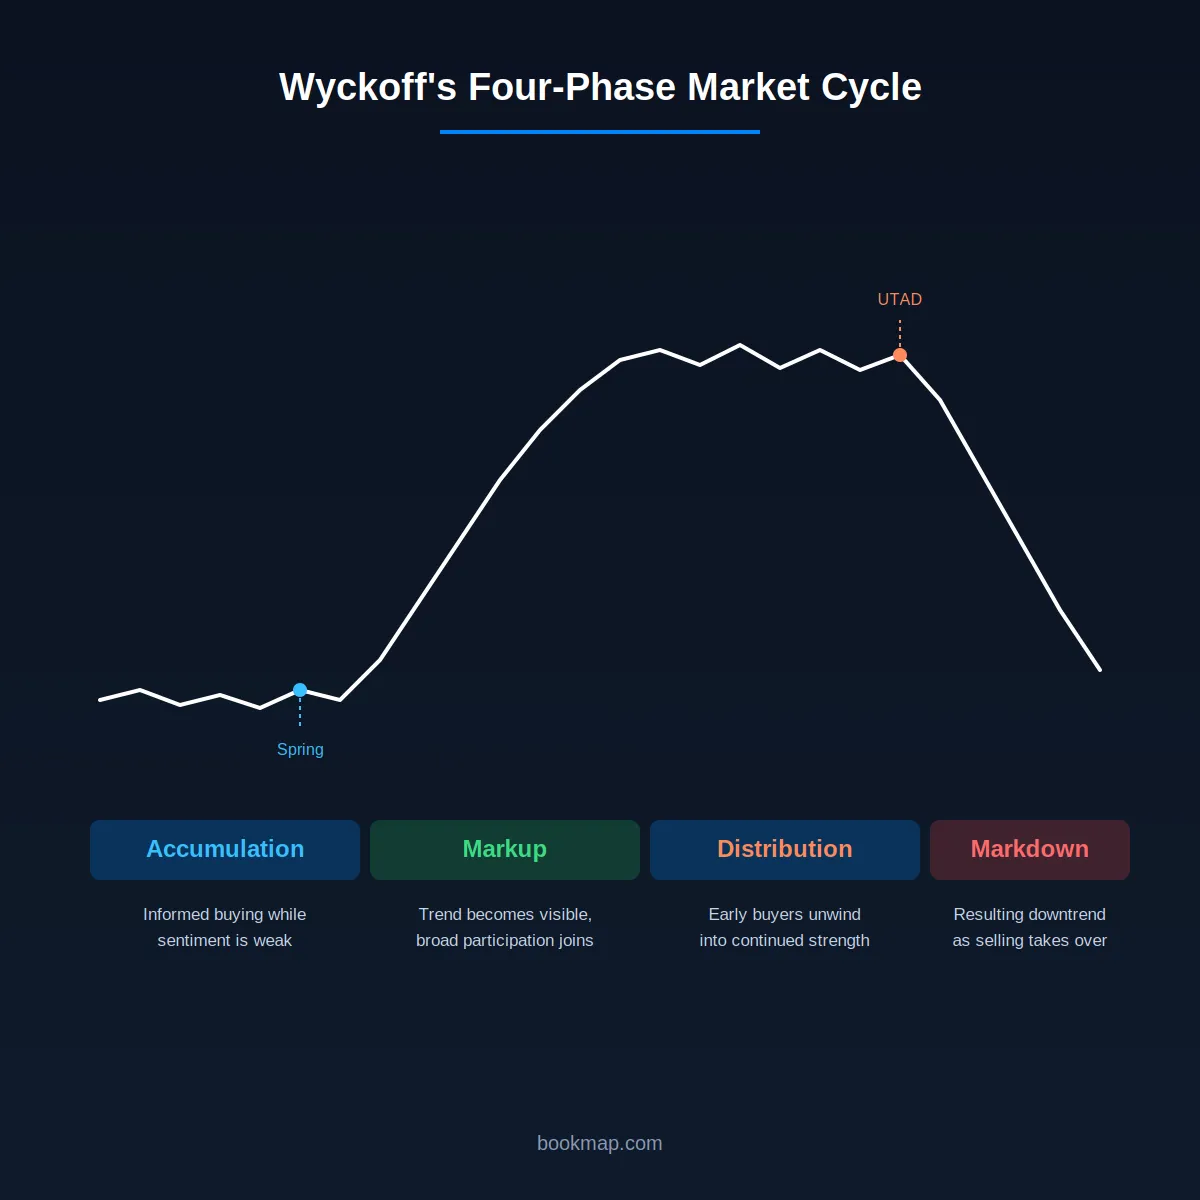
Wyckoff’s model specifically includes named sub-patterns within accumulation and distribution — a “spring” (a brief false breakdown below the accumulation range, designed to trigger stop losses and shake out weak hands before the real move up) and a “UTAD” or upthrust after distribution (the equivalent false breakout above a distribution range). These sub-patterns are essentially an early, formalized version of the liquidity-sweep concept covered above, predating the “smart money concepts” terminology by roughly a century.
Institutional Algorithmic Trading Strategies
Institutional algorithmic trading strategies focus on execution quality rather than prediction. These algorithms manage order timing, size, and placement based on real-time liquidity conditions. Rather than chasing price, they respond to how the order book evolves and how other participants interact with liquidity.
For traders analyzing order flow, these algorithms often reveal themselves through repeated absorption, consistent liquidity placement, or sudden changes in depth as execution objectives are met.
Using Bookmap to Read Institutional Liquidity
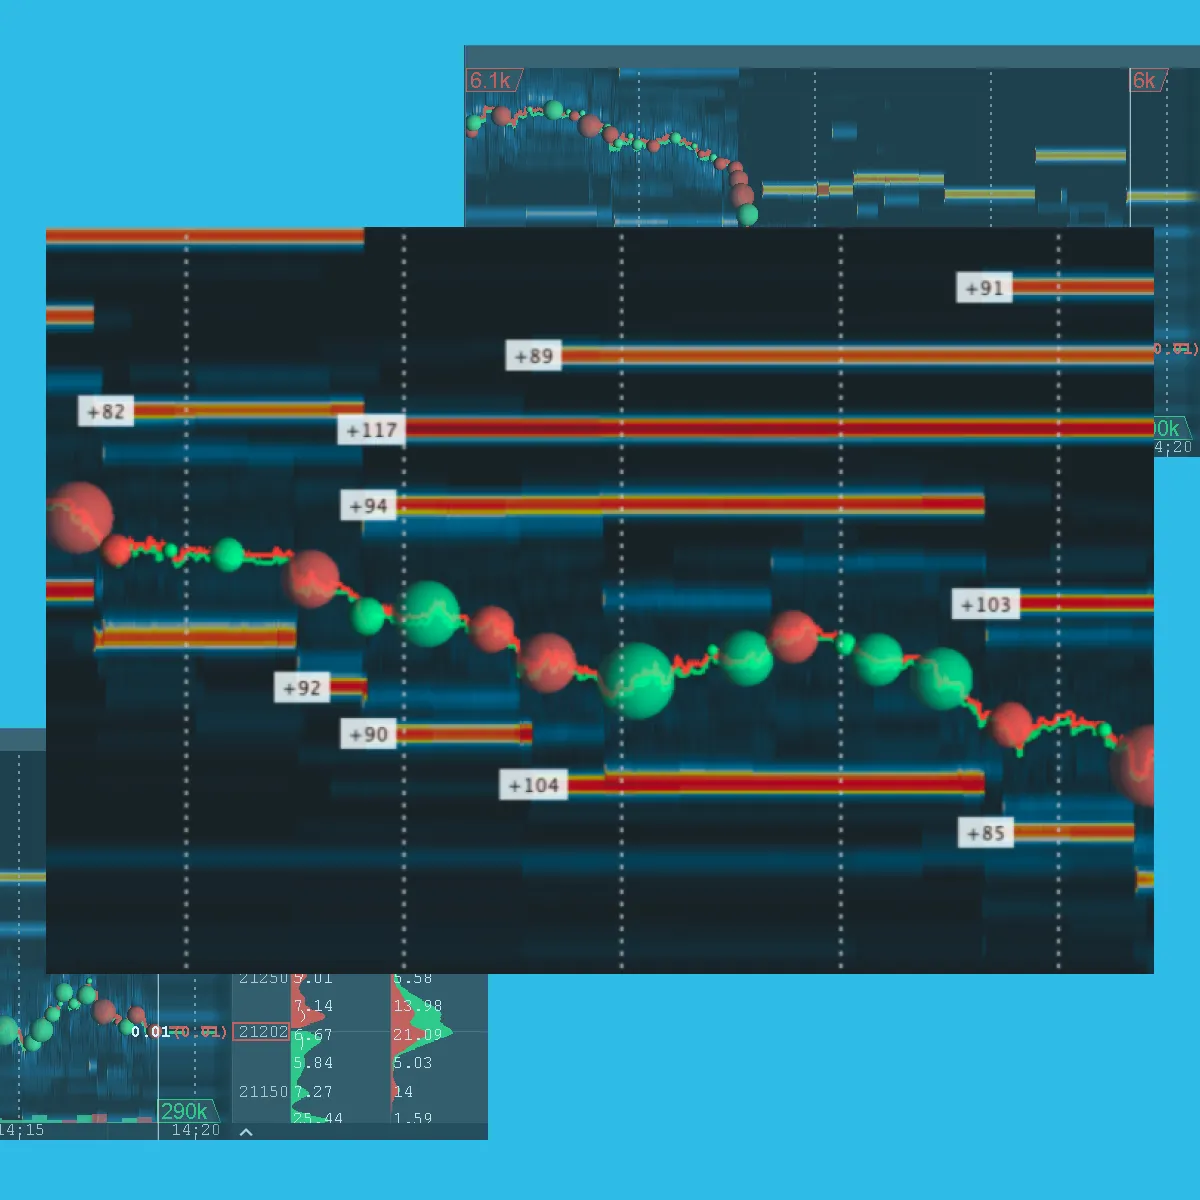
With Bookmap’s heatmap, traders can see:
- Where large bids and offers are sitting in real time.
- Whether liquidity is holding or disappearing (spoofing activity).
- How price reacts when it reaches a liquidity level.
Example:
If price approaches a large bid order at $4,000 and that liquidity remains firm, it suggests buyers are absorbing sell pressure. But if that liquidity disappears before price arrives, it could mean a fake wall was created to manipulate price.
How Institutions Execute Trades Without Moving the Market
Institutions use algorithms and execution strategies to prevent large orders from pushing price against them. Here’s how they do it:
A. Iceberg Orders: Hiding Large Trades
- Iceberg orders allow institutions to disguise their true order size by only showing a fraction of it on the book at any given time.
- Retail traders who aren’t using order flow tools won’t see the hidden size behind an iceberg, leading them to misread supply and demand.
How Institutions Hide Their Orders
Institutions rarely place their full order size directly into the market. Instead, they rely on algorithmic execution strategies designed to reduce signaling risk and minimize market impact. Large orders are broken into smaller executions and routed over time, interacting with visible and hidden liquidity.
Techniques such as iceberg orders, passive absorption, and liquidity-seeking algorithms allow institutions to execute size while remaining difficult to detect using price alone.
📌 How to Spot Icebergs in Bookmap:
- Look for repeated small orders absorbing large amounts of liquidity at a key level.
- Use the Stops & Icebergs tool to identify whether institutions are placing hidden buy or sell orders.
B. Liquidity Absorption: Identifying Strong Support & Resistance
Institutions absorb liquidity at key price levels to build or unload positions without alerting the market.
How This Looks in Bookmap:
- Strong liquidity remains at a level despite multiple price tests → Sign of true institutional demand/supply.
- Price moves toward a level and liquidity disappears before impact → Sign of potential spoofing or fake orders.
Example:
A hedge fund wants to accumulate 1 million shares of a stock but doesn’t want to drive the price up. Instead of buying everything at once, they slowly absorb liquidity at a key support level over multiple hours or days.
Retail traders who only follow price action might not see this happening, but order flow traders can spot aggressive buying with liquidity absorption in Bookmap.
VWAP, TWAP & Institutional Order Execution Strategies
Two of the most common institutional execution algorithms are built around time and volume rather than price prediction:
- VWAP (Volume-Weighted Average Price) execution splits a large order into smaller pieces sized to match the market’s actual volume pattern throughout the day, aiming to execute at or near the day’s volume-weighted average price rather than any single moment’s price.
- TWAP (Time-Weighted Average Price) execution instead splits the order into equal pieces spread evenly across a fixed time window, regardless of volume patterns — simpler than VWAP, and sometimes preferred specifically because it’s less predictable to other participants trying to detect a large order in progress.
Both are benchmark-driven, not prediction-driven: the goal is executing close to a fair average price with minimal market impact, not timing an entry for maximum profit. Retail order flow tools can sometimes spot the signature of one of these algorithms running — a series of similarly sized orders arriving at consistent intervals is a common tell for TWAP specifically, similar to the kind of repeating footprint covered in Bookmap’s guide to spotting stop order clusters.
Dark Pools, Block Trades & Alternative Trading Systems
Not every large institutional trade happens on a public exchange. Dark pools are private trading venues, operated by exchanges, banks, or independent operators, where large orders can be matched without displaying size or price to the public order book beforehand — reducing the market-impact and front-running risk of showing a large order on a visible exchange. Block trades are large, privately negotiated transactions, often executed off-exchange or through a dark pool, then reported to the tape after the fact per regulatory requirements.
Both fall under the broader category of Alternative Trading Systems (ATS) — SEC-regulated venues that aren’t traditional exchanges but still facilitate trading. Retail order flow tools, including Bookmap, generally can’t see dark pool activity directly, since by design it isn’t part of the visible order book — worth knowing as a real limit on what any order flow tool, however good, can show. For more on separating what order flow can and can’t reveal about the broader trend, see Bookmap’s guide to reading market trends through order flow analysis.
Institutional Trading and Market Structure
Institutional trading plays a central role in shaping market structure. Large-scale portfolio adjustments, risk management activity, and capital rebalancing all contribute to liquidity shifts that influence price movement. These actions are part of normal capital markets activity and are continuously reflected in order flow and depth-of-market behavior.
Understanding this context helps traders interpret why markets transition between balance and imbalance and why liquidity often precedes price movement.
Trading Alongside Institutional Players: Key Strategies
While retail traders can’t move the market like institutions, they can position themselves in ways that align with institutional activity.
A. Trade Off Liquidity Zones, Not Just Price Action
Many retail traders chase breakouts or react to price movements, but institutional traders focus on liquidity levels instead.
📌 How to Adjust Your Approach:
- Identify major liquidity levels before entering a trade.
- Watch how price reacts at those levels—does liquidity get absorbed, or does it disappear?
- Use Bookmap’s Cumulative Volume Delta (CVD) to confirm if buyers or sellers are truly in control.
B. Understand Market Sweeps & Trapped Traders
Institutions will often push price into liquidity zones to trigger stop losses and force retail traders to exit at bad prices.
📌 How to Avoid Getting Trapped:
- If price sweeps through a liquidity level but fails to follow through, it may be a false breakout or reversal signal.
- If price sweeps through and continues with strong momentum, institutions are likely still accumulating.
Example:
A large buy wall appears at $100 on a stock. Price sweeps through it aggressively but fails to continue higher. This signals a possible fakeout, meaning sellers are still in control.
Retail traders who blindly buy breakouts without checking liquidity could end up trapped, while those reading the order flow correctly can fade the move and short at a premium price.
Common Institutional Trading Strategies
Pulling together the execution methods covered throughout this guide, institutional trading strategies generally fall into a few recognizable categories: benchmark-driven execution algorithms (VWAP and TWAP, aimed at minimizing market impact rather than predicting price), off-exchange execution (dark pools and block trades, used to move large size without showing it on the public book), and position-building over time (the accumulation and distribution behavior described in Wyckoff’s model, executed today through a combination of iceberg orders and algorithmic execution rather than manual buying).
None of these strategies are secret or exotic — they’re publicly documented execution methods. What’s genuinely difficult for a retail trader to replicate isn’t the strategy itself, but the capital and infrastructure needed to execute at institutional scale. For a grounded look at what retail traders can actually take from this, see Bookmap’s 3 steps to trading success.
How to Track Institutional Holdings & 13F Filings
Institutional investment managers with more than $100 million in Section 13(f) securities are required to file Form 13F with the SEC quarterly, disclosing their equity holdings within 45 days of each quarter’s end. This is publicly available data — searchable directly on the SEC’s EDGAR database — and it’s the most direct way to see what a specific fund actually holds, rather than inferring it from order flow.
The major limitation is timing: because of the 45-day filing window, 13F data is disclosing positions that are already six weeks old by the time they’re public, and funds may have already changed those positions by the time anyone reads the filing. 13F data is useful for understanding a fund’s general positioning and strategy over time — it’s not useful for timing a trade around what a fund is doing right now.
Common Myths About Institutional and Smart Money Trading
A few widely repeated claims about institutional trading are worth pushing back on directly:
- “Every order block or liquidity sweep is institutional activity.” Many of these patterns occur naturally from ordinary retail and algorithmic activity with no large player involved at all — treating every instance as confirmed institutional footprint overstates what a candlestick pattern alone can actually prove.
- “Spoofing is common and undetectable.” Spoofing is illegal under U.S. law and actively prosecuted by regulators; while it does happen, treating every disappearing order as spoofing rather than a legitimate cancellation is a common overinterpretation.
- “Institutions always know where price is going.” Institutional traders manage execution risk on size they’re already committed to — that’s a different skill from predicting direction, and institutional order flow is not evidence of superior forecasting ability.
- “You need to trade exactly like an institution to succeed.” Retail traders don’t face the same market-impact constraints institutions do, which means strategies built specifically around minimizing market impact (like VWAP execution) solve a problem retail traders mostly don’t have. A retail account is generally better served focusing on the fundamentals covered in Bookmap’s guide to position sizing for success than on imitating institutional execution mechanics.
Conclusion: Applying Institutional Trading Techniques to Your Strategy
Institutions don’t trade based on indicators or lagging signals—they trade based on liquidity, market structure, and order flow dynamics. Retail traders who learn to read liquidity, spot absorption, and track iceberg orders can gain a huge advantage over those who rely solely on price action.
How to Apply This to Your Trading
✔ Use Bookmap’s heatmap to find true support & resistance levels based on liquidity.
✔ Watch for iceberg orders and absorption to confirm if a level is being defended.
✔ Track sweeps and false breakouts to avoid getting trapped.
✔ Align your entries with institutional execution strategies for better trade timing.
📌 Want to improve your ability to track institutional activity? Compare Bookmap Plans Here.
FAQ
What is institutional trading?
Institutional trading involves large-scale market participation by banks, hedge funds, asset managers, and other professional firms. These participants focus on efficient execution, liquidity management, and minimizing market impact.
How do institutions execute large trades without moving the market?
Institutions use algorithmic execution methods that divide large orders into smaller pieces. These methods interact with visible and hidden liquidity over time to reduce price disruption.
How can traders identify institutional liquidity zones?
Institutional liquidity zones often appear where price reacts repeatedly or where liquidity remains present despite heavy trading. Observing absorption, holding behavior, or sudden liquidity removal can provide clues.
Do institutions rely on indicators when trading?
Institutions primarily rely on liquidity, order flow, and execution behavior. Indicators may provide context, but execution decisions are driven by real-time market conditions.
Are institutional traders mainly banks or hedge funds?
Institutional traders include banks, hedge funds, asset managers, pension funds, and proprietary trading firms. While their objectives differ, their execution constraints are similar.
What is the difference between VWAP and TWAP execution?
VWAP splits an order into pieces sized to match the market’s actual volume pattern throughout the day, aiming for the volume-weighted average price. TWAP splits the order into equal pieces spread evenly across a fixed time window regardless of volume. Both are designed to minimize market impact rather than predict price direction.
Can retail traders see dark pool activity?
Not directly. Dark pools are private venues where large orders are matched without displaying size or price on the public order book beforehand. Order flow tools, including Bookmap, show visible exchange activity — they can’t see dark pool trades before they’re reported.
What is a 13F filing and how current is the data?
A 13F is a quarterly SEC filing required from institutional managers with over $100 million in Section 13(f) securities, disclosing their equity holdings. Filings are due within 45 days of quarter-end, so the data reflects positions that are already about six weeks old by the time it’s public — useful for understanding a fund’s general strategy, not for timing a trade around current positioning.
Are order blocks and liquidity sweeps reliable trading signals?
They’re pattern-based inferences about where institutional activity might have occurred, not direct observations of actual orders. They can be useful context, but treating every instance as confirmed institutional footprint overstates what a candlestick pattern alone can prove.
What is Wyckoff’s accumulation and distribution model?
A market cycle framework describing four phases — accumulation, markup, distribution, and markdown — theorized to reflect how large participants build and unwind positions over time. It predates modern “smart money concepts” terminology by roughly a century and includes similar concepts, like the “spring” and “upthrust,” describing false breakouts designed to trigger stop losses before the real move.
Sign Up Now
Latest Articles