


See block trades more clearly in real time.
Compare plans to access deeper market visibility for block trades.
Stocks
October 3, 2026
Updated
The Impact of Block Trades on Stock Prices: What Retail Traders Should Know
Have you ever wondered how a single trade could make a stock dive or surge in seconds? This magic happens due to something called “block trades.” Here, the big players (like hedge funds and pension funds) make moves that can shake up the market.
Do you wish to know how? Read this article to learn what block trades are and why they matter, not just for institutional investors but also for everyday traders.
We’ll start by exploring how block trades work and why they are often conducted away from public exchanges. You’ll see how institutions use methods like dark pools to keep these massive transactions hidden. Also, we’ll discuss the impact these trades have on stock prices and market liquidity, especially in low-volume stocks. For those wondering how these large trades influence volatility and why prices can swing so wildly, we have answers.
Finally, we’ll cover how retail traders can use advanced tools, like our platform, Bookmap, to monitor block trades and adjust their strategies. Let’s get started.
Table of Contents
- What Are Block Trades?
- Large-Scale Securities Transactions: How Block Trades Fit In
- What Is the Minimum Share Threshold for Block Orders?
- How Do Institutional Desks Price Block Transactions?
- The Impact of Block Trades on Stock Prices
- Block Trades in Low-Volume Stocks: Higher Impact
- How Institutions Execute and Place Large Blocks
- How Retail Traders Can Respond to Block Trades?
- Conclusion
- FAQs
What Are Block Trades?
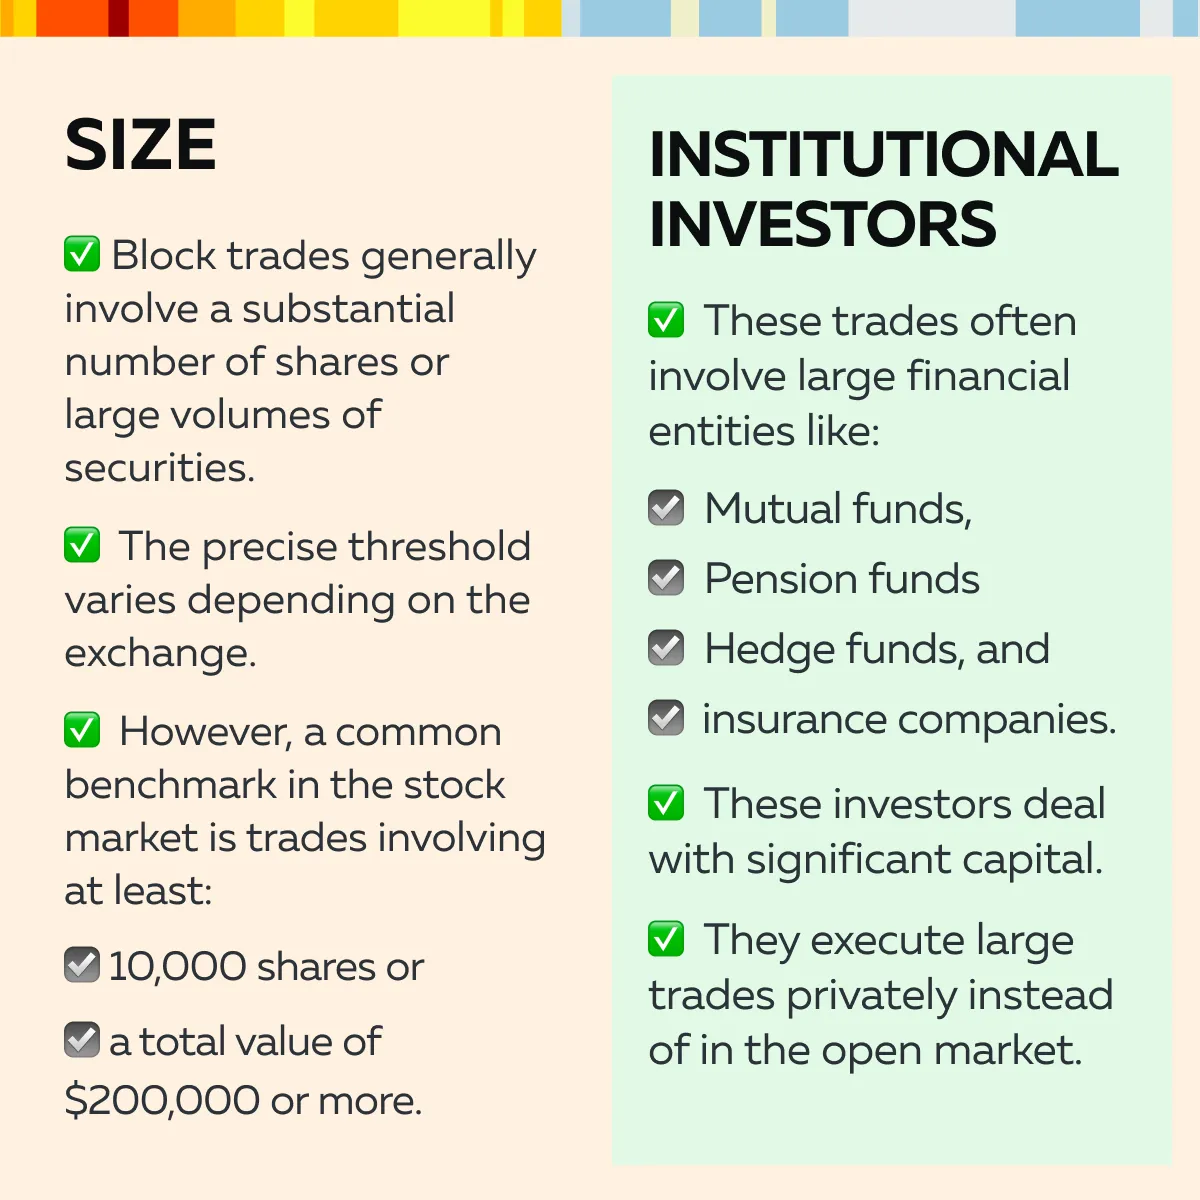
Block trades refer to large, privately negotiated transactions involving the buying or selling of significant quantities of a stock or other security. These transactions are mostly executed outside of the public exchange. The reason for executing block trades outside the regular market is to minimize the impact such large orders could have on the stock’s price. For more clarity, let’s have a look at some characteristics of block trades:
Why Block Trades Occur Privately?
When a massive order is placed in the open market, there is always a possibility of price fluctuations. This happens due to supply and demand dynamics. For example,
- Let’s consider that a hedge fund tried to purchase 1 million shares of stock in the open market.
- This purchase increases the demand for the stock.
- This increased demand also surges the stock price up before the order is fully executed.
- As a result, the transaction becomes more expensive for the buyer.
- In contrast, selling a substantial block of shares could depress the stock price.
To prevent these price disruptions, block trades are arranged privately. They usually happen through brokers or investment banks. These intermediaries find a buyer or seller willing to transact the large block at an agreed price without it being visible on the public exchange.
Now, let’s enhance our understanding and study an example of a block trade:
Let’s consider that a hedge fund wants to purchase 1 million shares of Company XYZ. If they placed this buy order directly on a public exchange, the surge in buying demand would likely increase the stock price before the entire order could be fulfilled.
To avoid this, the hedge fund negotiates the transaction privately. They negotiate with a broker who facilitates the block trade. This approach helps maintain a stable price, and the hedge fund gets a better deal. The broker may:
- look for a seller willing to provide all the shares later
or
- break up the block trade into smaller components to place them strategically on the market at their discretion.
Large-Scale Securities Transactions: How Block Trades Fit In
A large-scale securities transaction is any trade big enough that the way it is executed changes its cost. Block trades are the best-known example, but the same pressure shapes several related terms that are often used loosely. This section separates them.
Institutional Block Order
A block order is the instruction: a fund tells its broker it wants to buy or sell a large position. A block trade is what results when that order, or part of it, executes as a single large print. The two are not the same. A 2 million share order can be filled as one negotiated block, as hundreds of small child orders over several days, or as a mix of both. The tape records the executions and never shows the parent order, which is why a single large print is rarely the whole story.
Bulk Equity Crossing
A cross matches a buy order and a sell order against each other without sending either to the open market. Crosses come in a few forms:
- Agency cross: the broker matches two clients’ orders and acts only as an intermediary.
- Principal cross: the broker buys from one client with its own capital and later sells to another.
- Venue cross: two orders meet inside a dark pool or another matching system, usually at or near the midpoint of the national best bid and offer.
Crossing keeps both orders out of the public book, which is the point, and it is why the trade appears on the tape only after it happens.
Wholesale Securities Trading
In finance, wholesale means institution to institution, as opposed to retail trading by individuals. Wholesale securities trading covers block trades, interdealer trading and trades between asset managers, banks and market makers. Wholesale financial market transactions are the same thing seen from the market’s side.
Do not confuse this with “wholesalers,” the market makers that buy and fill retail orders from brokers. Both operate off exchange, but a block between two institutions and a retail order filled by a wholesaler are different transactions. For the retail side, see Bookmap’s guide to payment for order flow, and for the venues institutions use, see dark pools and dark pool transactions.
What Is the Minimum Share Threshold for Block Orders?
There is no single threshold, but there is a standard one in US equities. Under SEC Regulation NMS, an order has “block size” if it is at least 10,000 shares or covers stock with a market value of at least $200,000. Meeting either test is enough. At $50 a share, 4,000 shares reach $200,000 and qualify. At $5 a share, 10,000 shares qualify on the share test, at $50,000.
In practice, desks also look at size relative to the stock. A block in a mega-cap that trades tens of millions of shares a day is a modest order for that stock, and 10,000 shares in a thinly traded small-cap can be a large part of a day’s volume. That is why the same regulatory “block” can have very different price impact.
Other markets set their own thresholds:
| Market | How block size is set |
| US stocks | Regulation NMS definition: 10,000 shares or $200,000 |
| Futures (CME) | Minimum block quantity set product by product under CME Rule 526 |
| Options | Each exchange sets its own minimum sizes for block or large-size trades |
| Corporate bonds | No fixed block size, but the sizes of very large trades are capped in public data |
How Do Institutional Desks Price Block Transactions?
A block desk prices a block by asking what it will cost to get rid of the position afterward. The main inputs:
- A reference price. Usually the last sale, the closing price, a volume-weighted average price or the midpoint of the national best bid and offer, depending on the trade.
- Size relative to liquidity. A block that is a small share of average daily volume can be placed close to the market. One that is many days of volume needs a wider discount or a longer timeline.
- Risk and capital. If the desk commits its own capital (a “risk bid”), it prices in the chance that the stock moves against it before it can resell. If it works the order as an agent, the client carries that risk and the desk charges a commission instead.
- Information content. A seller who may know something the market does not is a worse risk than an index fund rebalancing.
- Market conditions. Volatility, the spread and recent news all widen or narrow the discount.
- Hedging cost. The desk may hedge with futures, options or a basket while it resells.
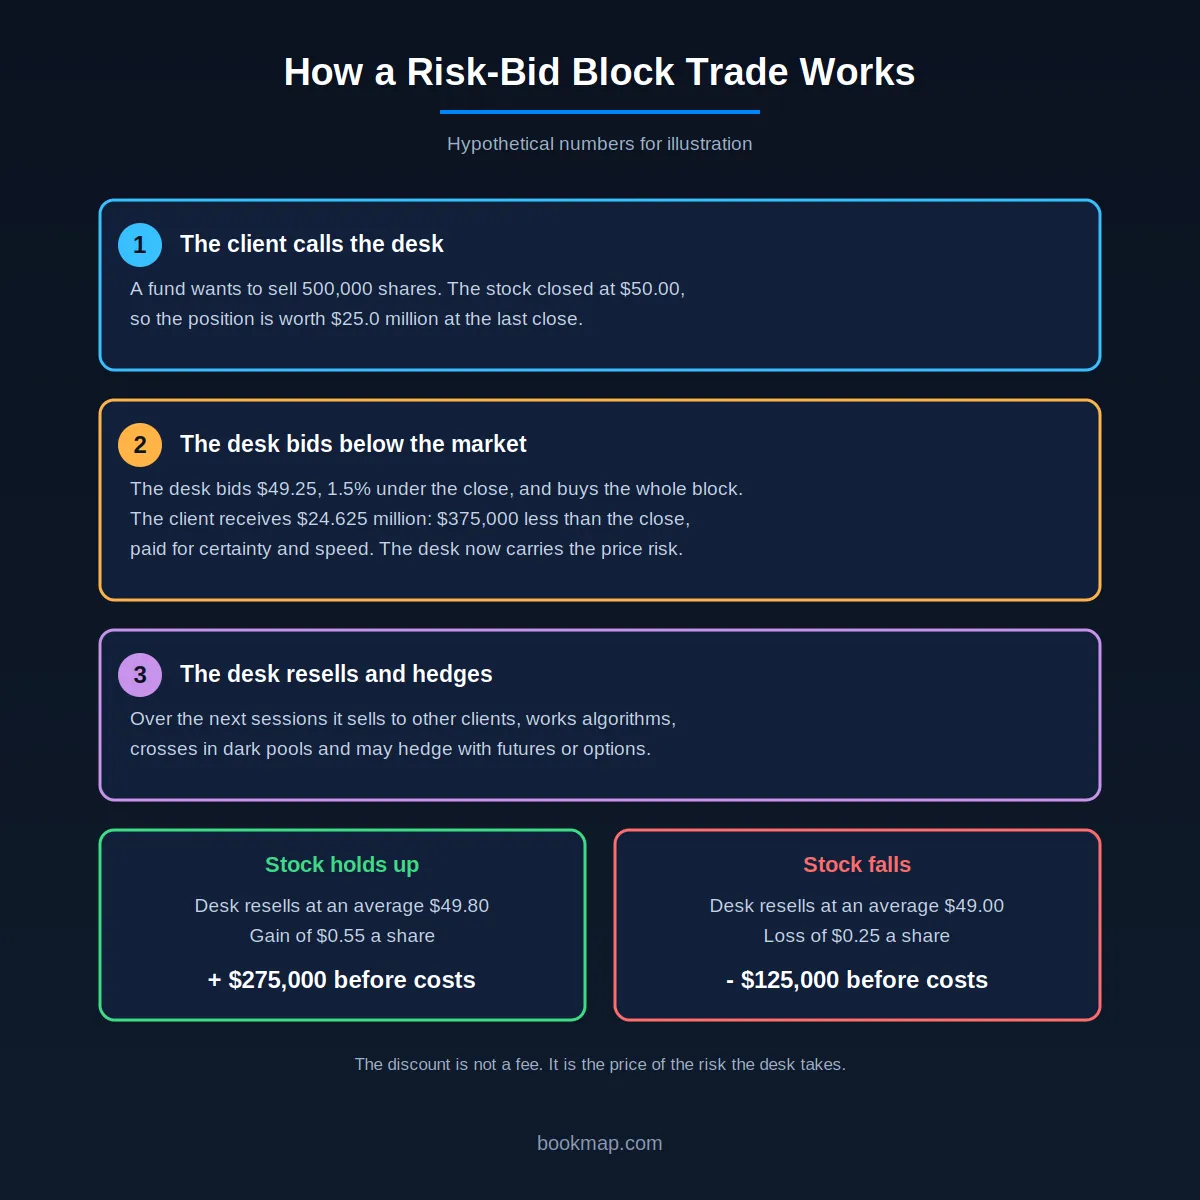
Hypothetical numbers show the logic. A client wants to sell 500,000 shares of a stock that closed at $50.00. The desk bids $49.25, 1.5% below the close, and the client receives $24.625 million instead of $25 million, paying $375,000 for certainty. The desk now owns the stock. If it sells the position at an average of $49.80 over the next sessions, it earns $0.55 a share before costs, or $275,000. If the stock falls and it averages $49.00, it loses $0.25 a share, or $125,000.
The discount or premium is therefore not a fee. It is the price of the risk the desk takes. A well-known study of block trading by Keim and Madhavan also found that prices tend to move in the weeks before a block trades, consistent with information leaking as the block is shopped around. That is one reason desks and clients prefer to limit how many counterparties they approach.
The Impact of Block Trades on Stock Prices
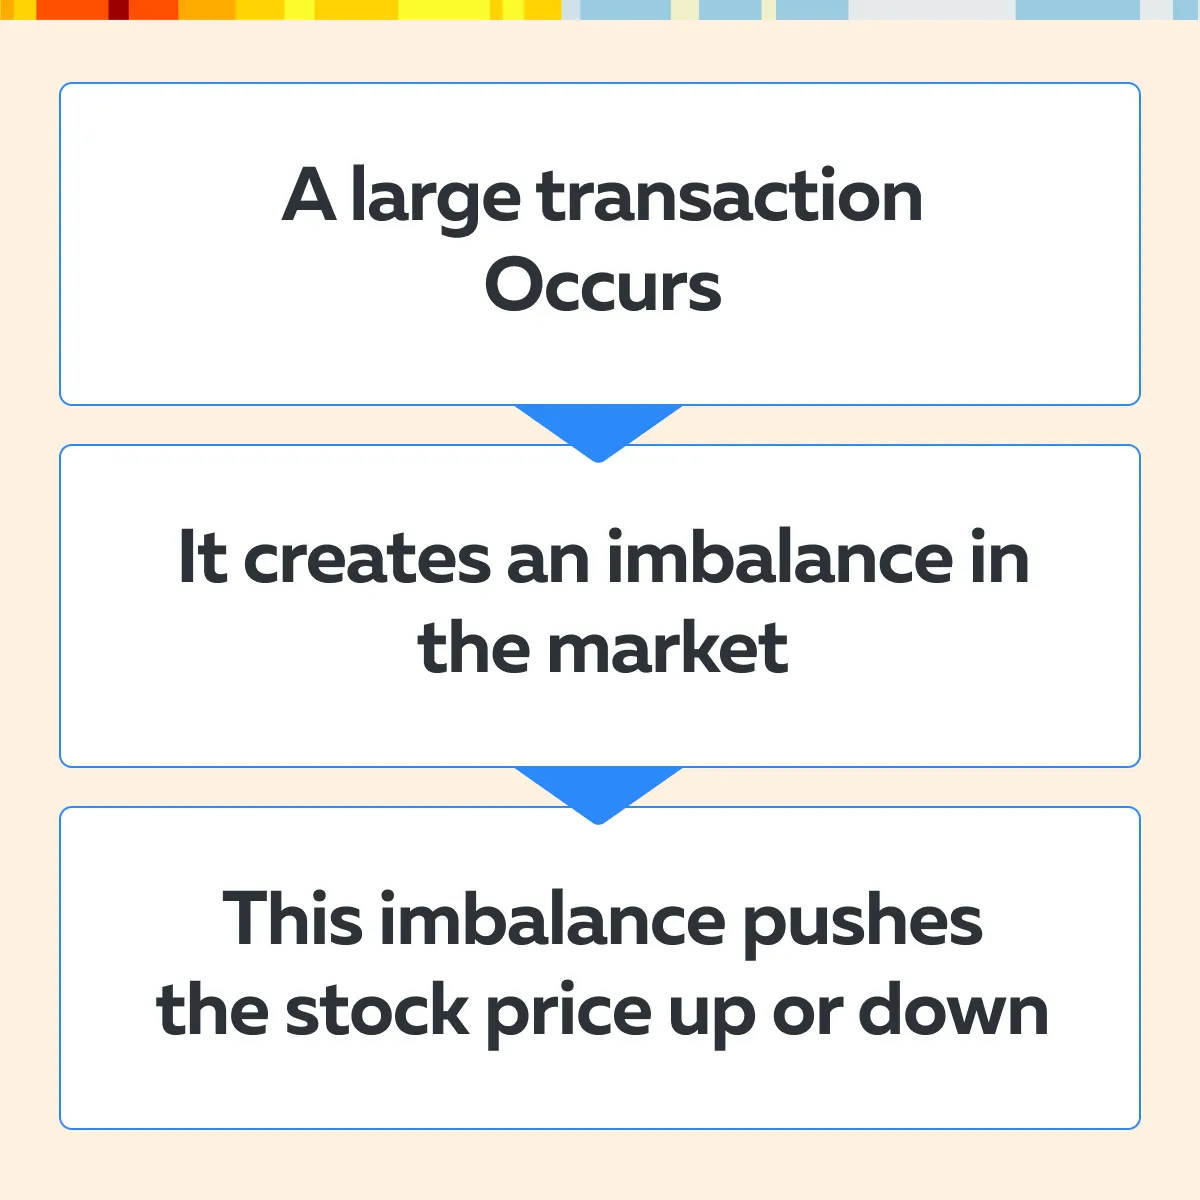
Be aware that block trades can significantly influence stock prices. Their effect is felt even more in cases where the stock is relatively low in trading volume and lacks ample liquidity. This effect is closely linked to the basic economic principles of supply and demand. Check the graphic below:
How Do Block Trades Affect Prices?
It must be noted that stocks that have lower daily trading volumes are more susceptible to price fluctuations when faced with large trades. In these stocks, even relatively small orders have a notable impact on the price. So, a large order that is worked carelessly in the open market can cause sharp price movements, which is why block trades are usually negotiated or spread out over time.
Moreover, a block trade creates an excess of supply or demand that the market struggles to absorb immediately. Let’s understand better through two different scenarios:
| Scenario I: Buy-Side Block Trade | Scenario II: Sell-Side Block Trade |
|
|
The scenarios above describe a large order that reaches the open market. A negotiated block works differently. It matches a buyer and a seller directly, so it does not eat through the public order book. The price pressure shows up later, when the dealer that took the block resells or hedges it, or when the other side starts working its new position.
Let’s also check out an example scenario:
- Let’s consider that there is a low-volume stock.
- It usually trades only a few thousand shares per day.
- In this stock, an institutional investor decides to execute a buy-side block trade of 100,000 shares.
- The demand for stock increases dramatically.
- Given the limited liquidity, this trade temporarily drives up the stock price.
- Most buyers scramble to meet the sudden demand.
- Contrarily, if there is a sell-side block trade, it causes a steep price drop.
- This happens because the influx of shares on the market exceeds the typical daily demand.
What is the Effect of Block Trades on Market Liquidity?
Liquidity refers to how easily shares can be traded without causing any significant fluctuations in the stock’s price. When a large institutional investor executes a block trade, the liquidity on either the bid or ask side of the order book is usually reduced. This affects the trading conditions for other market participants. Let us read how this might occur.
| Consumption of Order Book Depth | Effect on Bid-Ask Spreads | Slippage |
|
|
|
For more clarity, let’s check out an example:
- Say that a mutual fund places a large buy-side block trade for an illiquid stock.
- This trade consumes most of the shares available at the current ask prices.
- This increases the share price.
- Market makers adjust to the reduced supply of shares.
- Retail traders who attempt to buy the stock after this block trade experience slippage.
- Their orders get filled at higher prices.
- Additionally, they see a wider bid-ask spread.
- This makes it more expensive to trade for them.
In this way, block trades create a less favorable environment for regular market participants. Generally, the significant consumption of liquidity due to block trades alters normal market conditions.
This section describes blocks that are worked in the lit market. A block that is crossed off exchange between two parties does not consume the public order book. If you see liquidity thin out on a heatmap, it more likely points to orders being worked on lit venues than to a negotiated block.
How Do Block Trades Affect Underlying Stock Volatility?
The effect depends on how the block is executed, how big it is relative to the stock’s volume, and what the market thinks the trade means.
- Negotiated blocks usually cause less volatility than the same size worked in the open. A cross matches supply with demand directly, so it does not eat through the lit order book. The price pressure arrives later, when the desk resells or hedges the position.
- Temporary and permanent effects differ. Research on block trades finds a temporary component, the price pressure from needing liquidity, and a permanent component, the information the trade reveals. Classic studies found that the permanent effect is larger for block purchases than for block sales, which tend to recover more.
- Leakage can move price before the print. If word of a large order spreads while it is being shopped, price can drift before the trade appears on the tape.
- Illiquid stocks feel it most. The same trade is easily absorbed in a mega-cap and can move a small-cap by several percent.
- Volatility around the print is often about interpretation. Traders react to a large print, and the reaction can be larger than the information in the trade.
Block Trades in Low-Volume Stocks: Higher Impact
Block trades have a deep impact on the prices of low-volume stocks. In low-volume stocks, fewer shares are actively traded on a regular basis. The lack of liquidity in these stocks means that even a relatively small number of shares can significantly influence the stock’s price. Now, when it comes to block trades, the effect is even more dramatic. Let’s read about the major impacts block trades usually have.
Impact I: Exaggerated Price Effects
In highly liquid stocks, such as Apple or Microsoft, which trade millions of shares daily, block trades are usually absorbed with minimal impact on the price. However, low-volume stocks do not have this level of market depth. This makes them far more sensitive to large trades. When a block trade occurs in such stocks, it causes a significant price swing.
For example:
-
- Let’s assume that a hedge fund executes a $5 million block trade in a low-volume stock.
- This stock mostly trades only $1 million worth of shares per day.
- This sudden influx of buying or selling pressure pushes the stock price up or down by 5% or even more.
- Be aware that the percentage change entirely depends on the existing order book and market conditions.
- In comparison, the same $5 million trade in a high-volume stock like Apple would have a negligible impact.
- That’s because the market could easily absorb the trade without disrupting the price.
Impact II: Volatility Consideration
Block trades in low-volume stocks also increase price volatility. The sudden and substantial price movements create unpredictable trading conditions. This makes it more difficult for retail traders to:
- anticipate price trends
or
- set effective stop-loss and take-profit orders.
This added volatility is particularly challenging for traders who prefer stable price patterns. Deliberately moving a stock’s price with large trades in order to profit from the move is market manipulation, which is illegal. Legitimate block trades are priced and executed to limit price movement, not to create it. What retail traders see is the volatility around a large print and the hedging and resale that follow it, which can make price harder to predict and stops harder to place.
How Block Trades Are Executed?
Mostly, block trades are executed off-exchange. Such an execution minimizes the market impact of large transactions. Usually, this process involves using dark pools or private negotiations between large financial institutions. This setup ensures that their large trades are handled efficiently and discreetly. Let’s understand both these setups of off-exchange trading in detail:
| Dark pools | Private negotiations |
and
|
|
For example:
- Say a pension fund wants to sell a substantial number of shares in a company.
- If the sale were to occur openly on the stock market, it could lead to a sharp drop in the stock price.
- Instead, the pension fund uses a dark pool to sell the shares discreetly.
- This setup minimizes the market impact.
- Retail traders are kept unaware of the transaction details.
- This reduces the risk of front running.
Want to track large institutional trades in real-time? Use Bookmap’s advanced market analysis tools to gain insight into block trades.
What is the Market Impact Post-Execution?
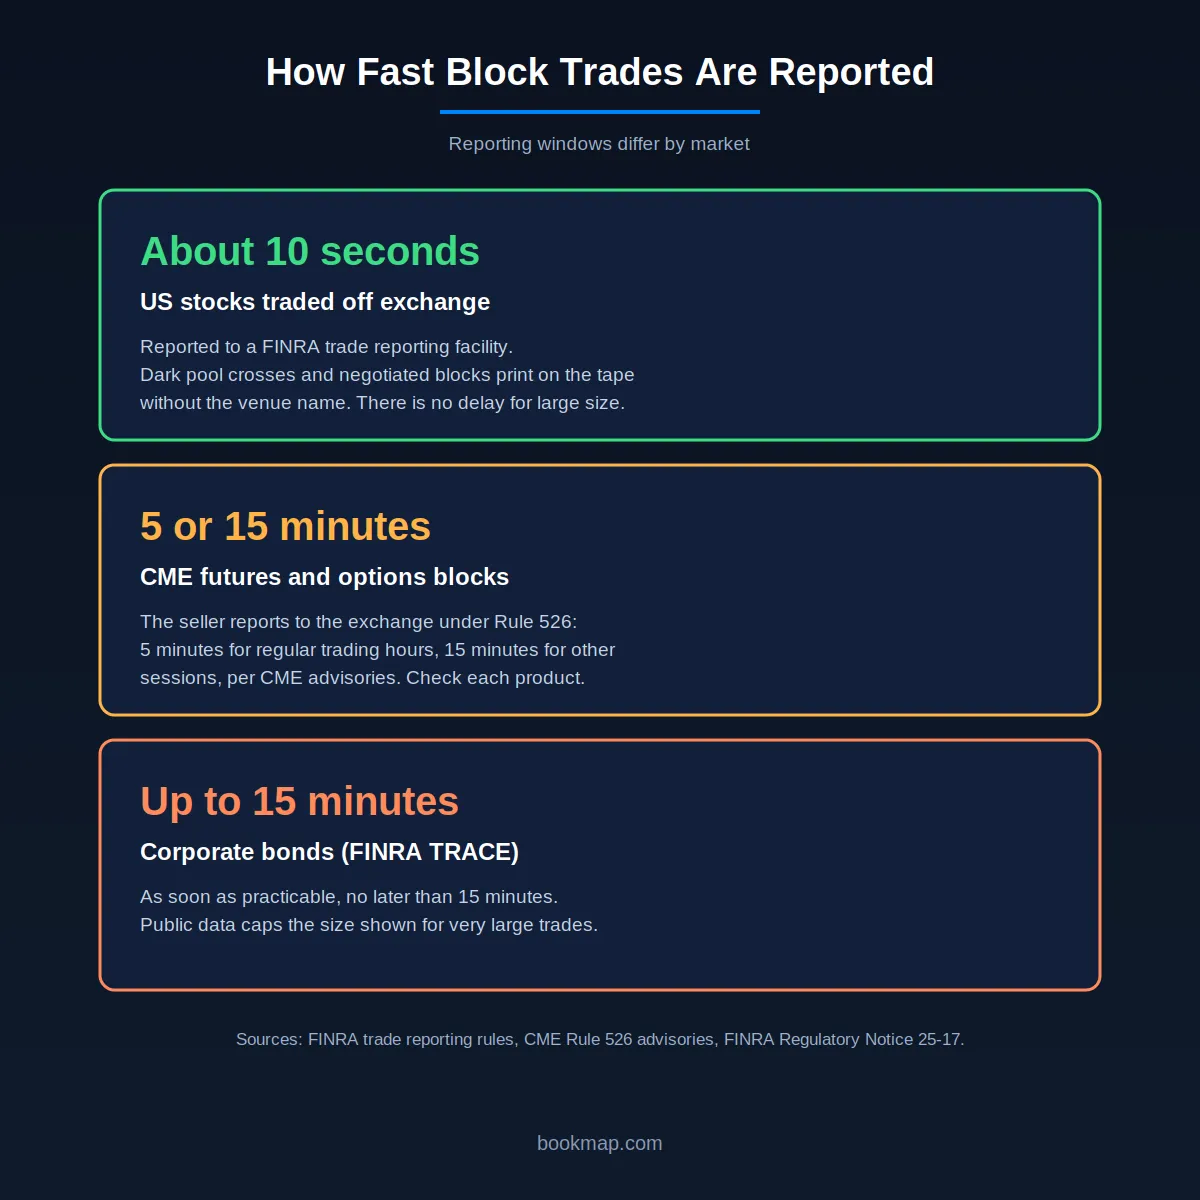
Although block trades are executed off-exchange, they still affect the stock’s price once reported. By regulation, an off-exchange trade in a listed stock must be reported to a FINRA trade reporting facility, generally within 10 seconds, and it appears on the consolidated tape without the venue’s name. When the details of a block trade become available, the market may react significantly.
Once the block trade is made public, retail traders and other market participants often respond based on the information. If a print looks like an institutional purchase, some traders read it as confidence in the company’s future performance, but the tape does not say who bought or why. This prompts traders to buy more shares. This spike in buying pushes the price higher. On the other hand, a print that looks like a large sale can be read as bearish, although block sales also come from index rebalances, portfolio transitions, hedges and sponsor sell-downs that say little about the company. This leads to additional selling pressure.
What Reporting Timeframes Apply to Institutional Crosses?
Reporting rules depend on the market:
| Market | Rule | Timeframe |
| US stocks traded off exchange, including dark pool crosses and negotiated blocks | Reported to a FINRA trade reporting facility | Generally within 10 seconds of execution |
| US stocks traded on exchange | Reported by the exchange to the consolidated feed | Immediately |
| CME futures and options blocks | Reported to the exchange by the seller under Rule 526 | Within 5 minutes for blocks in regular trading hours and within 15 minutes for other sessions, per CME advisories |
| Corporate bonds and similar debt | Reported to FINRA’s TRACE system | As soon as practicable, and no later than 15 minutes after execution |
US equities have no delayed reporting for block trades: a large stock block prints within seconds, without the venue name. Futures and bond markets allow a longer window. In bonds, the public display also caps the size of very large trades, so a very large investment grade trade shows as “5MM+” and not as its true size.
How Institutions Execute and Place Large Blocks
Institutions choose a method based on urgency, size and how much information they are willing to reveal. The sections below cover the main routes, from algorithms to overnight offerings.
Institutional Trade Execution Strategies
The usual toolkit, from the least to the most price-sensitive:
- Participation algorithms (VWAP, TWAP, percentage of volume) release small pieces over time. They suit orders that are a modest share of daily volume.
- Implementation shortfall and liquidity-seeking algorithms trade faster when liquidity appears and slower when it does not.
- Dark pool and conditional-order crossing looks for a large counterparty without showing the order.
- High-touch block desks negotiate a size trade directly, sometimes with the bank’s capital.
- Overnight and marketed offerings handle very large stakes that the market could not absorb on a normal day.
An order that is a large share of average daily volume needs days to work or a block counterparty, and the more urgent the trade, the more it costs. For how institutional footprints show up in order flow, see Bookmap’s guide to trading like an institutional trader.
Capital Markets Volume Management
Large holders manage volume as well as price. Selling a big stake in one burst can move the stock, so holders stage sales over time or sell in blocks. Regulation sets some limits:
- Rule 144 volume limits. Company affiliates selling restricted or control stock under Rule 144 generally cannot sell more than the greater of 1% of the shares outstanding or the average weekly trading volume over the previous four weeks in any three-month period, and they file a Form 144 notice.
- Lock-up expirations. After an IPO, insiders are typically barred from selling for a set period, and the end of the lock-up can release a large supply.
- Registered offerings. A holder that wants to sell more than Rule 144 allows can register a secondary offering or sell through an overnight block, covered below.
Public Exchange Blocks vs. Dark Pool Crosses
Both routes move size, with different trade-offs:
| Public exchange | Dark pool cross | |
| Visibility before the trade | Displayed orders show in the book, and hidden or reserve orders show less | Orders are not displayed |
| Price | Set by exchange matching at displayed prices | Usually the midpoint of the NBBO, or within the quotes |
| Counterparty | Whoever is in the book | Other participants in the pool, which can be few at large size |
| Fill certainty | Higher for smaller pieces, but price impact is visible | Lower, because a matching counterparty is needed |
| Reporting | Exchange feed | FINRA facility, generally within 10 seconds |
| Best for | Smaller pieces and price discovery in liquid names | Large size where hiding intent matters |
Many institutions use both: they look for a cross in dark venues first and send what is left to lit exchanges.
NYSE Rule 127 Block Positioning Requirements
NYSE Rule 127 is no longer in the exchange’s rulebook. It was originally titled “Block Positioning” and later “Block Crosses Outside the Prevailing NYSE Quotation.” Under it, a member that wanted to cross a block at a “clean-up” price outside the current quote had to tell the specialist (later the designated market maker) first, trade with any better-priced interest in the book, and then cross the remaining shares at the clean-up price. A separate paragraph covered positioning, where the member took part of the block into its own account.
The NYSE amended the rule in 2010 to relax its restrictions and deleted it in 2020, along with other floor-era rules made obsolete by its Pillar trading platform. The rules that matter today are the exchange’s Pillar order rules, Regulation NMS and FINRA’s trade reporting rules.
“Block positioning” still exists as a business, though: a dealer that commits capital to take the other side of a client’s block is positioning it. The pricing section above describes the economics.
Over-the-Counter Privately Negotiated Block Crosses
Many blocks are negotiated “upstairs” by a broker’s block desk and not on an exchange. Here, over the counter simply means away from an exchange, and the trade is reported to FINRA like any other off-exchange trade. The process:
- The client calls the desk with the size and any limits.
- The desk looks for a counterparty among its clients, other institutions and dark venues, or commits its own capital.
- The parties agree a price, often by reference to the NBBO, a volume-weighted price or the close.
- The trade prints, generally within 10 seconds, without naming the parties.
The main risk is leakage. The more counterparties the desk approaches, the likelier the market is to infer a large order, which is why desks limit how widely they shop a block and why clients choose them partly for discretion.
Accelerated Bookbuild Secondary Offering Block Placement
An accelerated bookbuild (ABB) lets a large shareholder, such as a private equity sponsor or a founder, sell a big stake to institutions in one overnight session. It is related to a block trade but is a different product. How it typically runs:
- After the market closes, a bank is hired and the sale is offered to a small group of institutions, usually under confidentiality.
- The bank builds a book of bids overnight.
- The sale is priced before the next open, at a discount to the last close.
- The shares settle on the standard US cycle, currently T+1.
In a bought deal or risk block, the bank buys the shares from the seller first and resells them, so it carries the price risk. In a best-efforts deal it does not. Discounts to the last close vary with the size of the sale relative to normal volume, market conditions and demand, and industry guides commonly cite a few percent up to high single digits.
For other traders, the announcement is a supply event. Studies of secondary offerings generally find that the stock tends to trade lower on the news, and it can gap at the open, which is why traders watch for these offerings.
Crypto Institutional OTC Block Trading Desks
In crypto, large trades usually go through OTC desks and not the public order book. A desk quotes a price on request, the client accepts, and the trade settles away from the exchange book. The structure resembles an equity block desk, with differences:
- No consolidated tape. There is no single record of where or when a large crypto trade happened, and OTC trades may never print on a public feed.
- Counterparty and settlement risk. Settlement depends on the desk and the settlement method, not on a central clearing system.
- Pricing. Desks price off exchange order books and charge a spread that reflects size, volatility and their cost of hedging.
- Exchange alternatives. Large traders also use hidden or iceberg orders and execution algorithms on exchanges.
Because large OTC trades settle off the public book, a visible crypto order book is a partial picture. Bookmap’s crypto page covers the venues it connects to.
How Retail Traders Can Respond to Block Trades?
Retail traders are often at a disadvantage compared to institutional investors when it comes to:
- information
and
- trading speed.
However, they can still take strategic steps to respond to block trades. By monitoring and analyzing the effects of these trades, retail traders can make informed decisions. They can protect or even capitalize on market movements. Let us check out some popular tools.
What a Block Print Does and Does Not Tell You
A block print is easy to over-read. Four points to keep in mind:
- Every trade has two sides. A print means a buyer and a seller agreed on a price. The tape does not say which side initiated, and “block buy” or “block sell” labels are inferences, usually from whether the price printed near the ask or the bid.
- The reason is unknown. Blocks come from index rebalances, portfolio transitions, hedges, sponsor sell-downs, deal-related share sales and ordinary investment decisions. Most say little about the company.
- It is already done. Off-exchange blocks print after execution, and the price may have moved before you see it.
- It may not touch the order book. A block crossed off exchange does not remove liquidity from the lit book. A thinning bid or offer on a heatmap points to orders being worked on lit venues, which is a different thing.
Used carefully, large prints are context. They show where large participants have traded, and prices near them sometimes act as reference levels. They are not a signal to buy or sell on their own. For how hidden size and absorption look on a heatmap, see Bookmap’s guide to how to read and trade iceberg orders. The approaches described below are examples of how some traders respond, not recommendations.
Tools for Monitoring Block Trades
Retail traders can use various tools to stay informed about block trades:
- The consolidated tape and FINRA’s OTC Transparency data
Every off-exchange trade in a listed stock is reported to FINRA and prints on the consolidated tape, generally within 10 seconds, so large prints show up on any time and sales feed. Filtering a feed for large sizes shows block-sized activity as it happens, although the print does not name the venue or the parties. FINRA also publishes weekly volume by venue and stock, on a two-week delay for the most liquid stocks.
- Order Flow and Liquidity Analysis Tools
Our advanced market analysis tool, Bookmap, provides real-time insights into:
- market depth,
- order flow,
and
- liquidity.
Using it, retail traders can easily highlight significant shifts in supply and demand. This gives retail traders a clearer picture of how large orders, such as block trades, affect the market. For more clarity, let us see an example:
- Say a retail trader is using Bookmap.
- They notice a sudden depletion of liquidity on the buy side of the order book.
- This depletion can be consistent with a large sell order being worked on lit venues. A negotiated block crossed off exchange would not appear in the book at all.
- This insight helps the trader to decide whether to hold, sell, or hedge their position.
How to Respond to Block Trades?
Once a retail trader identifies a block trade, they can adjust their trading strategy. This reduces the impact of the trade. Here are some approaches:
Approach I: Managing Risk After Large Sell Orders
If a retail trader observes a large block sell trade in a stock they are holding, it indicates:
- bearish sentiment,
or
- unloading of a large block of shares by an institution.
In response, the trader could do the following:
| Exit or Reduce Their Position | Use Stop-Loss Orders |
| To manage risk, the trader might choose to sell some or all of their shares. They can follow this technique, especially if the block trade puts downward pressure on the stock price. | By setting a stop-loss order, traders can limit their potential losses. This gives protection when the price continues to decline following the block trade. |
Approach II: Capitalizing on Large Buy Orders
If a trader notices a substantial block buy trade, it signals institutional confidence in the stock. This could lead to a price increase. Now, the trader could:
| Enter or Increase Their Position | Monitor for Reversals |
| If the fundamentals align with the trader’s analysis, they might choose to buy or add more shares. By doing so, they can hope to benefit from the upward momentum. | Even after a large buy trade, prices can experience volatility. Retail traders should stay alert for any signs of a price reversal before committing fully. |
Let us understand better through an example:
- Say a retail trader notices on Bookmap heavy aggressive selling and a thinning bid in a stock they own.
- The trader sees that the bid side of the order book has thinned out.
- This situation suggests a price drop.
- To mitigate risk, they decide to:
- sell half of their position
and
- set a stop-loss order for the remainder at a strategic level.
- Alternatively, if the trader believes the block trade created an overreaction, they might wait for a chance to buy the stock back at a lower price.
Conclusion
Block trades are large and privately negotiated transactions. They are often used by institutional investors like hedge funds or mutual funds. Through these transactions, they buy or sell substantial amounts of stock without causing major disruptions in the market. These trades are usually executed off-exchange, using methods like dark pools. This keeps the institutions’ intentions hidden and prevents price movements that would otherwise occur if the trades were made in the open market.
However, block trades still have a significant impact on stock prices and liquidity, especially in low-volume stocks. When these large trades occur, they cause sudden and exaggerated price movements. This reduces available liquidity and increases volatility. Such a situation makes it harder for retail traders to predict price changes.
To monitor and optimize trading during these times, retail traders can use tools like the consolidated tape and our advanced market analysis tool “Bookmap.”Bookmap’s order flow and liquidity analysis can help you see how the lit market reacts around large activity.
FAQs
What is a block trade?
A block trade is a large, privately negotiated transaction in a stock or other security, usually arranged by a broker or investment bank and executed away from the public order book to limit price impact.
What is the minimum size for a block trade?
In US equities, SEC Regulation NMS defines block size as at least 10,000 shares or at least $200,000 in market value. Futures exchanges such as CME set minimums product by product.
How do block trades affect stock prices?
A block worked in the open market can move price, especially in low-volume stocks. A negotiated cross matches a buyer and seller directly, and the price pressure shows up later when the dealer resells or hedges. Research finds the permanent price effect is larger for block purchases than for block sales.
How are block trades reported?
Off-exchange trades in US stocks are reported to a FINRA trade reporting facility, generally within 10 seconds, and appear on the consolidated tape without the venue’s name. CME blocks are reported within 5 or 15 minutes, and corporate bond trades within 15 minutes.
How do institutional desks price block trades?
They start from a reference price and adjust for the size relative to normal volume, the risk and capital the desk takes on, the information content of the trade, market conditions and hedging cost. The discount or premium is the price of the risk.
What is the difference between a block trade and an accelerated bookbuild?
A block trade is a negotiated sale of a large position, often in the secondary market. An accelerated bookbuild is a form of block placement in which a bank markets a large stake to institutions overnight and prices it at a discount to the last close, with settlement on the standard cycle.
Can retail investors see block trades?
After they happen, yes. Large off-exchange prints appear on the tape within seconds, without the venue’s name. The order before it trades is never displayed.
Does a big block print mean the stock will rise or fall?
Not by itself. Every print has a buyer and a seller, the tape does not say which side initiated, and many blocks come from rebalances, hedges and sell-downs. Treat prints as context.
Are the block trade rules different for futures or bonds?
Yes. CME block trades are set product by product under Rule 526 and reported within 5 or 15 minutes. Corporate bond trades are reported to FINRA’s TRACE system within 15 minutes, and the sizes of very large trades are capped in public data.
What happened to NYSE Rule 127?
The rule, which governed block crosses outside the prevailing NYSE quotation, was amended in 2010 and deleted in 2020 as obsolete after the NYSE moved to its Pillar trading platform.
How do crypto block trades work?
Large crypto trades commonly go through OTC desks that quote a price privately and settle away from the exchange order book. There is no consolidated tape, so OTC trades may never appear on a public feed.
Sign Up Now
Latest Articles