


See market activity more clearly in real time.
Compare plans to access deeper market visibility for market activity.
Education
September 21, 2026
Updated
What is Flipping the Book in Trading?
You’ll see many variations of flipping in the markets, some illegal while others are not. Once you start objectively recognizing flipping activity, you’ll be able to take advantage of this phenomena and use it to your benefit.
According to the CME, flipping is defined as “the entry of orders or trade for the purpose of causing turns of the market and the creation of volatility or instability.” Flips require at least 2 orders: usually one aggressive order and a second cancellation of the opposite order, typically at the same price.
Table of Contents
- What Is Flipping the Book?
- Natural or Illegal?
- Flipping of the Book Examples
- Using Flipping of the Book in a Trading Strategy
- What Is Flipping in Trading? Mechanics, Strategies & Market Realities
- Scalping vs. Intraday Flipping vs. Swing Trading
- IPO Flipping: Capturing Day-One Listing Premiums
- FINRA Lock-Up Windows and Broker Penalty Bids
- High-Frequency Turnover in Digital Assets: Launchpads, Presales & NFTs
- Market Microstructure & Execution Risks That Erode Flipping Returns
- Regulatory Boundaries, Compliance & Tax Friction
- Trading Psychology: Avoiding Emotional Position Reversals and Churn
- Recognize Flips and Use Them
Natural or Illegal?
Flipping is the practice of enticing other market participants to join on one side of the market before the “flipper” turns and takes the other side.
Regardless of the fact that flipping of the book can be a manipulative practice, it can also be a natural event that occurs when buyers or sellers become locked in a position. For example, if buyers buy a level expecting the support to hold but the price breaks through, they may attempt to exit at the level in an attempt to at least get out at break even, posting sell limits which serves as a barrier at around the same price of the level and where they entered.
So, when is book flipping illegal? CME Rule 575 among other things, prohibits various disruptive trading activities on CME markets. The rule prohibits practices such as quote stuffing and spoofing. You can read more about spoofing in our article What is Spoofing in Trading?
When considering whether or not flipping violates rule 575, market regulation considers:
- The impact on other market participants
- Price fluctuations
- Market conditions in the impacted and related market(s)
- The participant’s activity in related markets
- Whether the flip involved the cancellation of a large order(s) relative to the existing bid/offer depth
- Whether repeated flipping turned the market back and forth (i.e., the first flip turns the market in favor of the offer/bid and the second flip turns the market in favor of the bid/offer)
(Source: CME Group site)
Please bear in mind that this rule 575 only applies to the CME—some markets have a slightly different rule or don’t have one at all. For instance, a lot of crypto trading is done “offshore” and in a decentralized manner, where such rules don’t apply since there is no enforcer.
Flipping of the Book Examples
The finest swing deals are rarely in the air. Swing traders appreciate having a support and resistance level working in their favor. However, they frequently lack a defined strategy for capitalizing on vendor support and resistance.
To develop a systematic trading strategy, we will look at “flipping support/resistance.” The conversion of support to resistance and vice versa is a regular occurrence in a moving market.
Broken Resistance Turned Support – Long Swing Trade
Whether or not the liquidity level, is also at a confluence of market structure such as a resistance level or trend line, a flipping of the book from offers to bids can also work just like a breakout and pullback to resistance-turned-support in traditional technical analysis trading, only with the added confidence that there is actually liquidity behind the level.
As price breaks through the level (highlighted by the green bubble of aggressive buying on the Bookmap chart below), price comes back to retest the level a few seconds later.
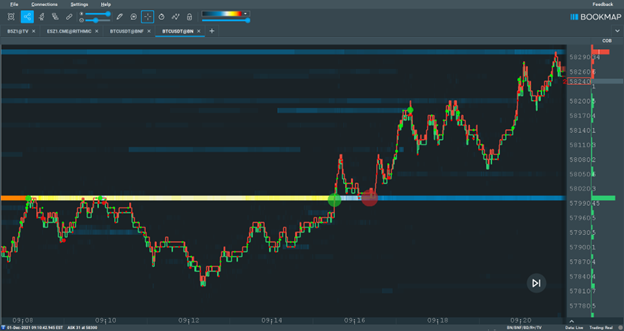
Notice how the offers (which are always above current price) immediately switch to bids (which are always below current price) at the same level when aggressive buyers manage to successfully penetrate the level.
On the retest, aggressive sellers (red bubble) are unable to break back down through these offers-turned-bids and the market proceeds to rally.
Broken Support Turned Resistance – Short Swing Trade
Flipping of the book naturally works in reverse, too, with passive orders setting on the bid flipping to the offer once price breaks down through the level.
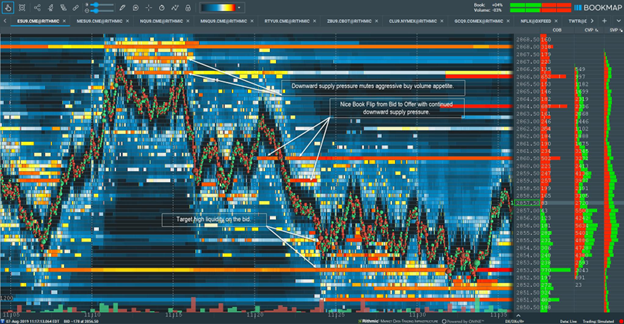
In the above example using the ES, you can see how aggressive sellers break through a level of bids before the level then immediately flips to offers and remains in the book for a significant period of time.
In this case, price doesn’t pull back to retest the level, but other traders will have likely noted this added resistance as price moved lower, which may have aided the aggressive sellers confidence in pushing prices lower.
Using Flipping of the Book in a Trading Strategy
There are countless trading strategies and it’s a vast subject. We have written about this previously, going through 7 different trading strategies and the pros and cons of each, titled How to Choose a Trading Strategy.
Flipping of the book is an order flow phenomenon—not a strategy. But it can be used within a trading strategy.
When looking at confluences within the broader market structure and any other analysis techniques you use (such as sentiment analysis, fundamentals, etc), flipping of the book can be just another confirmation of your analysis.
It can be also used as a method of risk management, whereby your exit for the trade has clearly defined parameters (e.g. placing your stop just below the offers-turned-bids) in whatever entry setup you utilize. How you use this in your trading plan is up to you, and should depend on your experience, risk tolerance, and backtesting or forward testing results.
What Is Flipping in Trading? Mechanics, Strategies & Market Realities
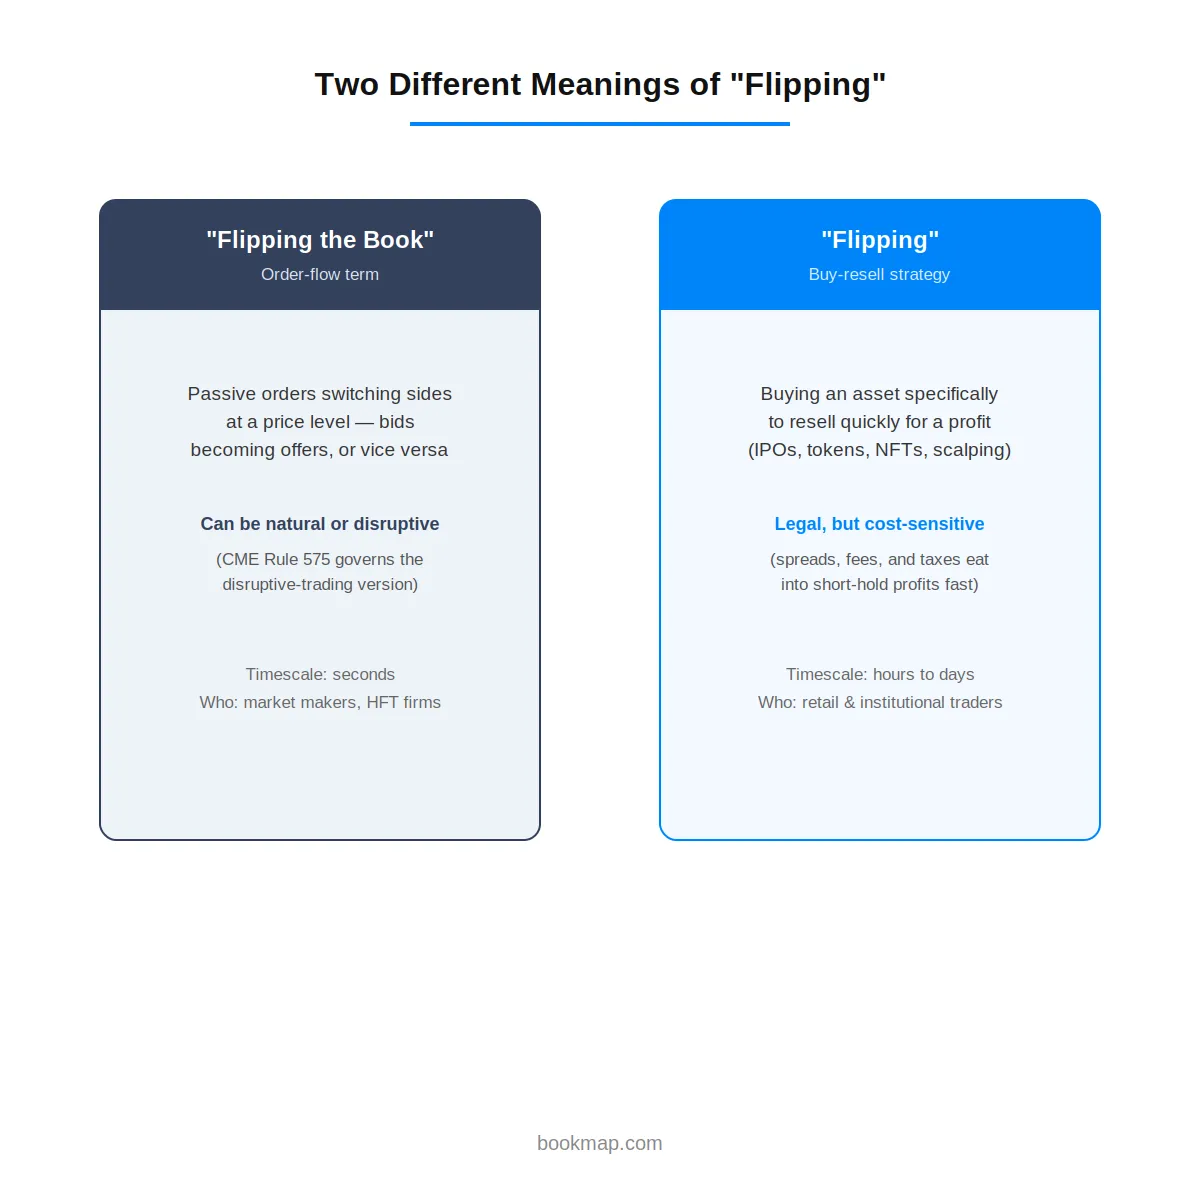
“Flipping” in trading has a second, unrelated meaning from the order-flow phenomenon covered above. In everyday trading and investing language, flipping means buying an asset with the specific intent of reselling it quickly for a profit — an IPO allocation sold on day one, a newly minted NFT resold within hours, a token bought in a presale and sold the moment it lists. It’s the same underlying idea as flipping a house, applied to a much shorter timeframe.
The connection to “flipping the book” above isn’t just wordplay: both describe rapid position turnover, and — as covered later in this section — aggressive flipping activity can shade into the same disruptive-trading territory that CME Rule 575 was built to police, particularly in fast, thin, or newly listed markets where a few large “flippers” can dominate the order book.
Scalping vs. Intraday Flipping vs. Swing Trading: Execution Comparison
| Scalping | Intraday Flipping | Swing Trading | |
| Typical hold time | Seconds to minutes | Minutes to hours | Days to weeks |
| Profit target per trade | Very small, high frequency | Small to moderate | Larger, less frequent |
| Primary risk | Cost stack (spread, fees) eating small margins | Execution risk, thin liquidity on new listings | Overnight/weekend gap risk |
| Where it’s common | Liquid futures, forex, large-cap stocks | IPOs, new token listings, NFT drops | Stocks, futures, crypto generally |
The common thread across all three is that shorter hold times amplify the impact of execution costs — covered in more detail in the market microstructure section below — since the same fixed cost stack gets paid far more frequently relative to the size of the expected profit.
IPO Flipping: Capturing Day-One Listing Premiums
IPO flipping means selling shares allocated in an initial public offering on the first day of trading (or shortly after), aiming to capture the “pop” — the gap between the IPO price and the price the stock actually opens at once public trading begins. This works because IPOs are frequently priced below where public market demand ends up settling, particularly for high-demand offerings, creating an immediate paper gain for anyone who received an allocation at the offer price.
The catch is allocation access: retail investors are typically allocated a small fraction of shares relative to institutional investors, and brokers who provide IPO access often track flipping behavior specifically, covered next.
FINRA Lock-Up Windows and Broker Penalty Bids
Two separate constraints limit IPO flipping in practice. Lock-up periods (typically 90–180 days) restrict company insiders and pre-IPO investors from selling — this doesn’t usually apply to retail investors buying at the public offering, but it shapes supply dynamics in the weeks following the IPO as the lock-up expiration approaches. Penalty bids are a separate mechanism: under FINRA rules, underwriters can impose a penalty on the broker (which the broker may pass on to the client) whose customer flips shares within a short window after the IPO, specifically to discourage the practice and stabilize the stock’s early trading.
Brokers that offer IPO access frequently track individual clients’ flipping history and may reduce or eliminate future IPO allocations for accounts that flip frequently — worth knowing before treating IPO access as a repeatable strategy rather than an occasional opportunity. For a related look at how retail order flow and broker incentives interact more broadly, see Bookmap’s guide to payment for order flow.
High-Frequency Turnover in Digital Assets: Launchpads, Presales & NFTs
Crypto and NFT markets have their own flipping ecosystem, structurally different from IPO flipping since there’s no underwriter, lock-up regulation, or penalty bid mechanism to speak of.
Token presales and DEX launchpads let early participants buy a token before it’s publicly listed, typically at a discount, with the intent of selling once trading opens on a decentralized exchange. The initial liquidity pool set up for that listing is usually thin relative to presale demand, which means the first trades after listing can move price dramatically in either direction — flippers selling into a thin pool can crash the price they’re trying to exit at, a self-defeating dynamic unique to how DEX liquidity pools are structured.
NFT floor price flipping means buying an NFT near a collection’s lowest listed price (“the floor”) and reselling quickly on renewed demand or hype. The practical risk specific to this market: NFT trading volume is unusually susceptible to wash trading (an entity trading with itself, often to farm rewards or fake volume), which can make momentum look stronger than genuine buyer demand actually supports. Distinguishing real floor-price momentum from wash-traded volume is difficult without on-chain analysis most retail flippers don’t do, which is a real and underappreciated risk in this specific corner of flipping.
Market Microstructure & Execution Risks That Erode Flipping Returns
Every flip pays a cost stack that a longer-term hold rarely has to think about, and it’s worth being concrete about what that stack actually contains:
- Slippage and bid-ask spread friction — the gap between the expected and actual fill price, and the cost of crossing the spread on both the buy and the sell. For a full breakdown of how spread mechanics work, see Bookmap’s guide to spreads in financial markets.
- Taker fees — most exchanges charge a higher fee for aggressively taking liquidity (crossing the spread) than for passively providing it, and a flipper buying and selling quickly is almost always paying the taker rate on both sides.
- Adverse selection and order routing — where an order actually gets filled, and by whom, affects execution quality in ways that aren’t always visible to the trader placing it. See Bookmap’s guide to payment for order flow for how broker routing incentives factor into this.
- Whipsaw-driven drawdown — frequent position flips in a choppy, directionless market mean paying the cost stack above repeatedly while netting little directional progress, which is one of the more common ways an otherwise reasonable flipping approach quietly erodes an account. Bookmap’s guide to position sizing for success covers how to size positions so this kind of repeated small erosion doesn’t compound into a serious drawdown.
None of these costs are exotic — they’re the same costs any active trading style pays. Flipping’s short hold times just mean they get paid far more often per dollar of intended profit.
Regulatory Boundaries, Compliance & Tax Friction
Flipping vs. disruptive trading: the existing CME Rule 575 material earlier on this page is directly relevant here — aggressive, rapid-turnover trading that specifically targets triggering other participants’ orders, rather than simply expressing a fast directional view, can cross into the same disruptive-trading territory that rule was built to catch. The distinction the CME itself draws (covered above: repeated flips turning the market back and forth, cancellations relative to existing depth) is a reasonable practical test for where legitimate fast trading ends and disruptive trading begins.
The Pattern Day Trader (PDT) rule applies directly to frequent flipping in a margin account: FINRA Rule 4210 requires $25,000 minimum equity for accounts making four or more day trades within five business days — a real constraint on how often stocks can be flipped in a smaller margin account. Cash accounts avoid the PDT rule but introduce a different constraint (settled-funds requirements, meaning proceeds from a sale aren’t immediately available to re-trade). See Bookmap’s futures contract mechanics guide for the full PDT breakdown, including why futures accounts aren’t subject to this rule at all.
Tax reality check: gains from assets held under a year (which covers virtually all flipping by definition) are taxed as short-term capital gains at ordinary income rates in the US — meaningfully higher than long-term capital gains rates for most tax brackets. The wash-sale rule adds a further trap: repeatedly buying and selling the same or a substantially identical security at a loss within a 30-day window can disallow the loss for tax purposes. This is general information, not tax advice — consult a qualified tax professional for guidance specific to your situation.
Trading Psychology: Avoiding Emotional Position Reversals and Churn
Flipping’s short feedback loop is a psychological trap as much as a financial one: a quick loss on one flip creates immediate pressure to “flip again” to recover it, which is a fast track to the exact whipsaw-driven drawdown covered above. Because flips resolve so quickly, there’s very little natural pause between trades to actually evaluate whether the last one was a good decision or a lucky/unlucky outcome — a distinction that matters enormously for whether repeating the same approach makes sense.
Bookmap’s guide to the psychology of pullbacks covers a related timing mistake that shows up constantly in flipping specifically, since the pressure to re-enter quickly after a loss is exactly when buying too early tends to happen.
Recognize Flips and Use Them
Flipping of the book is a disruptive (and sometimes illegal) practice that is all too common. Any serious order flow trader should have a strong grasp of what flipping looks like, who does it, and how it often plays out.
While most retail traders won’t be able to flip the book on most markets due to capital constraints, they can perhaps profit from it when they see it. Using Bookmap’s heatmap to see large players’ orders can help you gain an edge and define your risk, and flipping of the book is one of many order flow phenomena that give clear signals, as well as potential entry and exit points.
Sign Up Now
Latest Articles