


See market activity more clearly in real time.
Compare plans to access deeper market visibility for market activity.
Education
October 4, 2026
Updated
Don’t Get Slipped: A Short Guide to Slippage and Trading
Entering or exiting a trade, whether you are trading stocks, crypto or futures, you may find you get a different price than what you expected. This may be due to slippage. What is it and why?

Table of Contents
- What Is Slippage in Trading?
- What Causes Slippage?
- What Causes Slippage in Highly Volatile Markets?
- Slippage Examples
- Positive vs. Negative Slippage Examples
- How to Avoid Slippage
- How to Prevent Negative Slippage on Market Orders
- How to Configure Slippage Tolerance in Your Platform
- Slippage and Execution Quality
- Conclusion
- FAQs
Slippage occurs when a trade’s expected price differs from its executed price. In periods of higher volatility, slippage is more frequent.
What Is Slippage in Trading?
Slippage is the difference between the price you expected when you placed an order and the price at which it actually executed. It can be measured in price, in ticks or pips, or as a percentage, and it can work against you (negative slippage) or for you (positive slippage). It happens in every market: stocks, futures, forex and crypto.
Difference Between Expected and Executed Trade Price
The expected price is the price you saw when you decided to trade. Most traders use the best ask for a buy and the best bid for a sell at the moment the order is submitted, which is known as the arrival price. Some use the last trade price or the midpoint instead. The executed price is the average price at which the order actually filled.
The gap between the two is slippage. For a buy, paying more than expected is negative slippage. For a sell, receiving less than expected is negative slippage.
Order Execution Price Variance Explained
Order execution price variance is another name for the same gap. It comes from two sources, time and size:
- Time. Between the moment you click and the moment your order reaches the matching engine, quotes can change. In a fast market even a fraction of a second matters.
- Size. Each price level in the order book holds a limited amount of size. If your order is bigger than what is displayed at the best price, the rest fills at the next prices up or down the book, which is called walking the book.
Time is outside your control. Size is the part you can plan for.
How Slippage Works in Financial Markets
A market order trades against whatever is resting in the order book. The example below shows a market buy of 30 ES futures contracts against this hypothetical ladder of offers:
| Offer price | Size available | Contracts filled |
| 6,000.25 | 10 | 10 |
| 6,000.50 | 15 | 15 |
| 6,000.75 | 20 | 5 |
The average fill is about 6,000.46, which is 0.21 points, or about 0.8 ticks, above the 6,000.25 best offer you saw. At $50 a point, the 30 contracts cost $312.50 more than a fill entirely at the best offer. A 10-contract order would have filled at 6,000.25 with no slippage, and a larger order would have slipped more. Slippage that comes from your own size is called market impact.
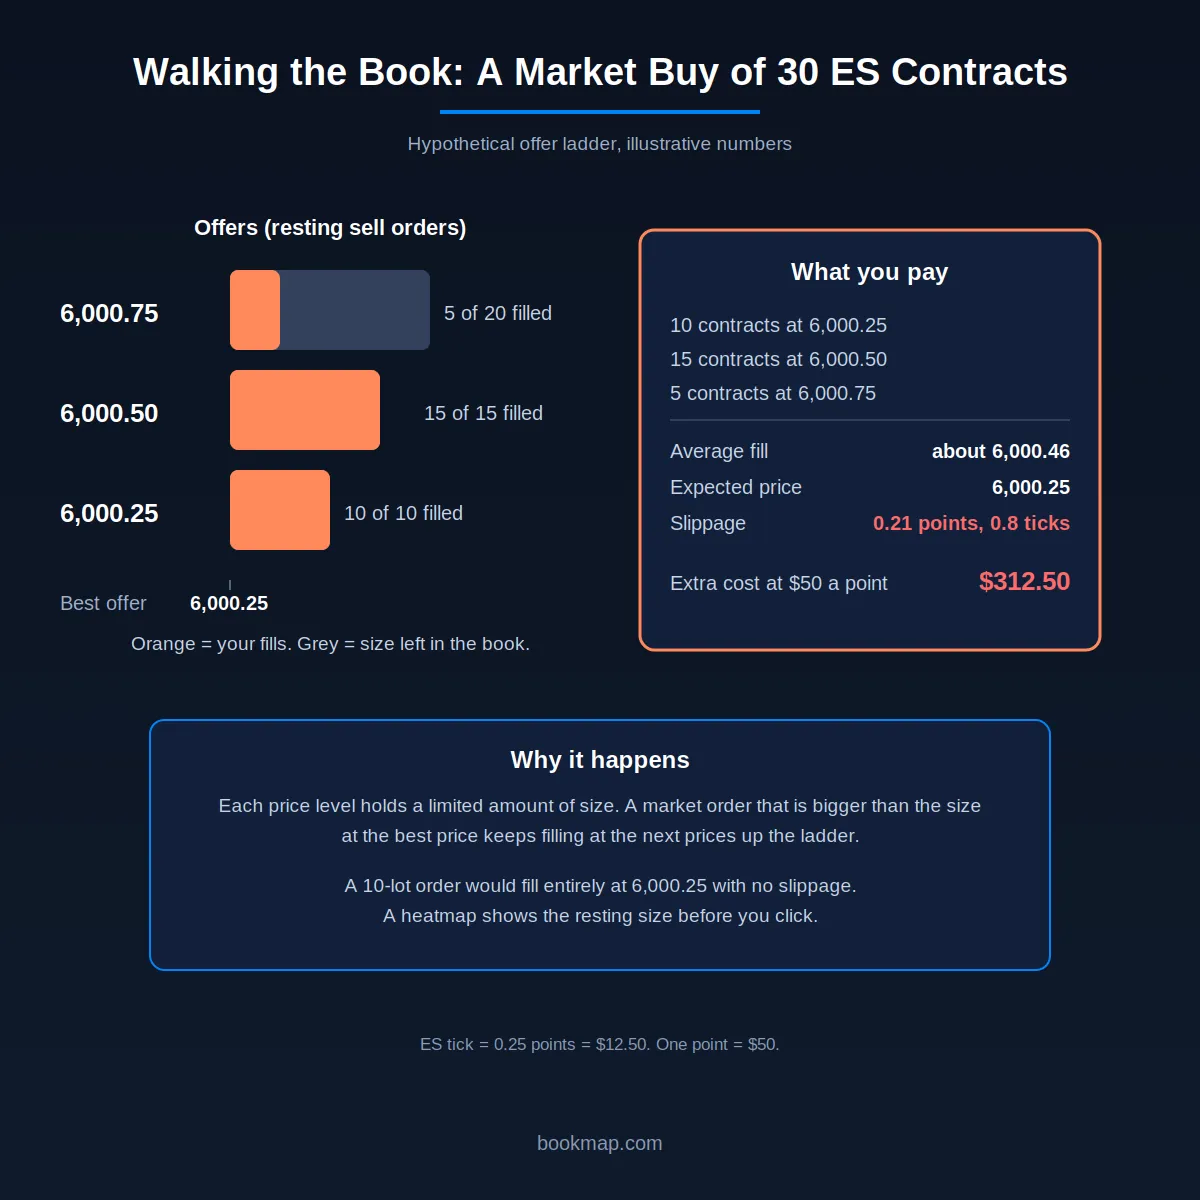
On a Bookmap heatmap, you can see the resting size at each price before you trade, which shows how far a market order of your size would walk. For more on how depth is displayed, see Bookmap’s guides to the heatmap and order book depth in day trading.
Slippage vs. Spread
New traders often confuse the two. The spread is the gap between the best bid and the best offer at one moment. Slippage is the gap between the price you expected and the price you got. If you send a market order, you cross the spread by design, which is a cost you can see in advance. Slippage is the surprise on top of it, when the spread widens, the price moves or your size walks the book. For the basics, see Bookmap’s guide to spreads in financial markets.
What Causes Slippage?
Any instrument price on any market venue is susceptible to slippage because of delays. Your order is in a queue and prices are changing. So, if the bid/ask spread changes by the time a requested market order hits the market, the order has to trade at the new price.
In markets with low liquidity, there is less size available at each price, so a market order may have to fill across several price levels. On the other hand, in a fast-moving, volatile market, the price of an instrument can change very quickly, before the order is filled.
What Causes Slippage in Highly Volatile Markets?
Volatility raises slippage through four channels:
- Faster price movement. Quotes change many times a second, so the price you saw is stale by the time your order arrives.
- Thinner books. Market makers and algorithms pull or shrink their quotes when risk rises. Displayed size at each level falls, and market orders walk further.
- Wider spreads. Liquidity providers widen their quotes to compensate for risk, which makes every market order costlier.
- Order flow surges. News, stop runs and liquidations send waves of market orders at the same moment, all competing for the same liquidity. During the October 2025 crypto liquidation cascade, more than $19 billion of positions were liquidated in about a day as market makers pulled quotes, which is slippage on an extreme scale.
Stops need special care. A stop-market order becomes a market order when triggered, so it takes whatever price is available, and in a fast move that can be far from the stop price. A stop-limit order caps the price but may not fill. For more on stop clusters, see Bookmap’s guide to stops.
Scheduled events produce the same pattern. For how order flow behaves around them, see Bookmap’s guides to economic events and order flow and trading in volatile times. For the crypto case, see liquidation cascades in crypto.
Slippage Examples
There is often slippage during or around announcements regarding interest rates, monetary policy, or company earnings releases and corporate announcements. In short, events can increase the chances of traders experiencing slippage.
This is usually because there is a lack of consensus about what this new, potentially vital piece of information means for the asset in question, resulting in liquidity providers and other market participants pulling their liquidity to avoid traders with a potential informational advantage. Often, retail traders don’t even know a piece of news has been released, resulting in trades executed at poor prices.
Another example where slippage occurs is the case of stop runs. A stop run is when multiple stop orders are triggered, often cascading and triggering even more stops and traders are forced to unwind their positions. The execution of these is based on queues and orders are filled on available passive liquidity.
Positive vs. Negative Slippage Examples
Slippage is not always a loss. Four hypothetical examples:
| Example | Order | Expected | Filled | Slippage |
| Negative, stock | Buy 500 shares at market | $42.00 | $42.07 on average | -$0.07 a share (-0.17%), $35 in total |
| Negative, futures | Sell 2 ES at market | 6,000.00 | 5,999.25 | -0.75 points, or 3 ticks, $75 in total |
| Negative, stop | Long 1 MES, stop-market at 5,990.00 | 5,990.00 | 5,988.50 | -1.50 points, or 6 ticks, $7.50 |
| Positive, limit order | Buy 1,000 shares, limit $20.00 | $20.00 | $19.98 | +$0.02 a share (+0.10%), $20 in total |
Positive slippage happens when the price moves your way between your click and the fill, or when a marketable limit order finds liquidity at a better price than its limit. It does not offset negative slippage automatically. Check how your broker treats it: in forex in particular, some brokers have been criticized for passing on negative slippage more often than positive, and policies differ.
Slippage by Market
The cause of slippage and the control you have over it depend on the market:
| Market | Main source of slippage | Main control |
| Stocks | Thin books in small caps, the open, news, orders that walk the book | Marketable limit orders and size relative to volume |
| Futures | Fast moves, stops triggered in clusters, thin overnight books | Market orders with protection, limit orders, size |
| Forex | Spread widening at rollover and news, weekend gaps | Avoiding illiquid hours, guaranteed stops, checking broker execution statistics |
| Crypto, centralized exchanges | Thin books on smaller pairs, liquidation cascades | Limit orders, size, liquid pairs |
| Crypto, decentralized exchanges | Pool price impact, delay, MEV bots | Slippage tolerance, MEV protection, splitting trades |
Slippage Tolerance Settings in Decentralized Crypto Exchanges
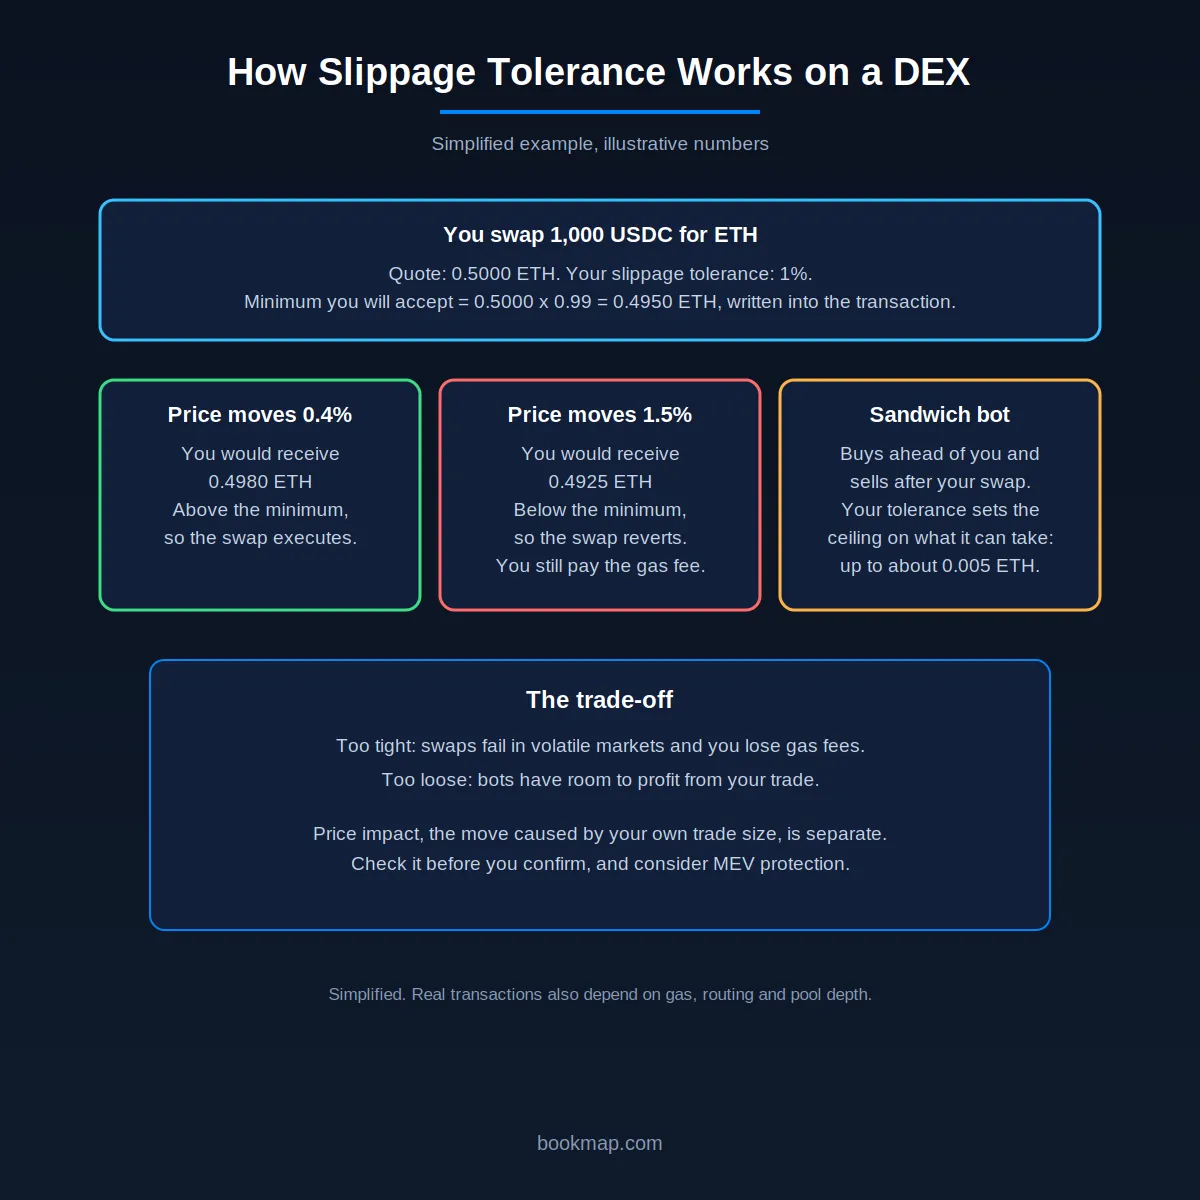
On a decentralized exchange (DEX) such as Uniswap, you set a slippage tolerance, the maximum price deviation you will accept from the quote. The setting converts into a minimum amount you must receive, which is written into the transaction. If the price moves past it before the transaction confirms, the transaction reverts: you pay the network gas fee but do not get the trade.
Two things drive slippage on a DEX that a central order book does not have:
- Price impact. Most DEXs price trades with a formula based on pool reserves, so your trade moves the price by an amount set by its size relative to the pool. This is mechanical, and you can see it before you confirm.
- Delay and MEV. Pending transactions wait in a public queue, and bots can trade around them. In a sandwich attack, a bot buys ahead of your trade, lets your swap execute at the inflated price within your tolerance, then sells.
That makes the setting a trade-off. A tolerance that is too tight makes transactions fail in volatile markets and wastes gas. One that is too loose gives sandwich bots room to profit, because your tolerance is the ceiling on what they can take. Uniswap’s old fixed default of 0.5% has been replaced by a default computed for each transaction, and an academic study of the change found it cut traders’ losses by about 55%. Private transaction routing and MEV-protection tools also reduce the exposure. See Bookmap’s crypto page for the venues it connects to.
Forex Broker Spread Widening and Weekend Slippage
Forex trades around the clock on weekdays, but liquidity is not constant, and slippage clusters in predictable places:
- Weekend gaps. The market closes on Friday afternoon (New York time) and reopens on Sunday afternoon. News over the weekend can open the market well away from Friday’s close. A stop order does not execute at the stop price in a gap. It executes at the first available price, which can be much worse. Some brokers offer guaranteed stops for a fee.
- Rollover. Spreads often widen for a short period around the 5 p.m. New York daily rollover, when liquidity thins.
- News releases. Central bank decisions and employment data widen spreads and thin the book within seconds.
- Broker execution model. Brokers fill market orders at their own quotes or pass them to liquidity providers, and spread and slippage policies differ. Check your broker’s execution statistics, and whether positive slippage is passed on.
Latency Slippage in High-Frequency Trading Algorithms
For algorithms, slippage is a latency problem. An algorithm decides on a quote, and by the time its order arrives, the quote has moved. Even microseconds matter when other firms are faster, which is why high-frequency firms pay for co-location and direct data feeds.
Latency slippage has three parts: data latency (how old the price is when the algorithm sees it), decision latency (how long the logic takes) and order latency (how long the order takes to reach the matching engine). Faster participants can pick off slower participants’ stale quotes, a form of latency arbitrage covered in Bookmap’s guide to what has changed in market microstructure.
Retail traders do not compete at that speed, but the same idea applies at human scale: the price on your screen is not the price at the exchange. Using real-time data, a stable low-latency connection and limit orders with protection all narrow the gap. Bookmap’s guide to real-time market data feeds covers the data side.
How to Avoid Slippage
The chances of getting slipped can be reduced in a number of ways.
The first and most obvious way is to trade markets with low volatility and high liquidity. A low volatility market indicates that the price will likely move less quickly. In contrast, a high liquidity market indicates that many active market players will be able to accommodate your transactions on the opposite side. As a result, your deal is more likely to be completed quickly and at the desired price if, for example, you trade when displayed depth is deep and spreads are tight, which is often outside the first minutes after the open and away from scheduled news. However, clearly, this is not always possible or may not even match your strategy.
Another option is not to trade just before, during, or immediately after important news events that cause extremely high volatility. This obviously does not apply to news traders, who make the bulk of their profits from such events. But even so, some may prefer to wait for the dust to settle and price direction to become clearer.
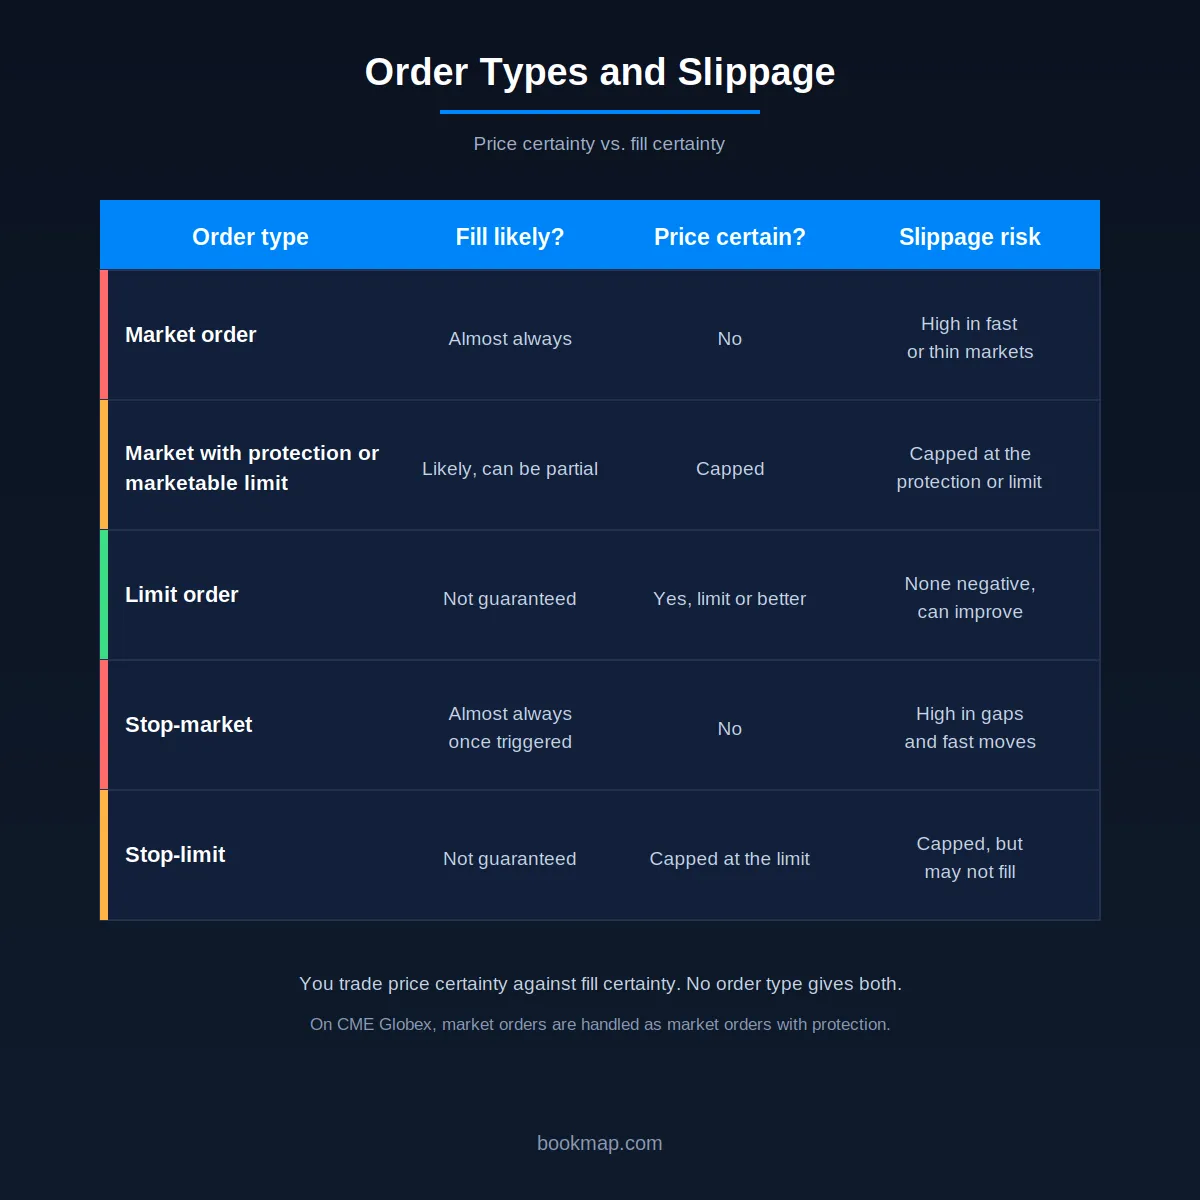
A third option is to use other order types, such as stop-limits or limit orders. With limit orders you are instructing an exchange that you want to, for example, sell a particular quantity but the order must not be executed at a worse price than you specify. A limit order is not guaranteed to fill completely, or at all, but any fill will be at your limit price or better. You may even experience positive slippage, where you get a more favorable price than expected.
How to Prevent Negative Slippage on Market Orders
You cannot remove slippage from a market order, because a market order promises a fill, not a price. You can limit how much it can cost:
- Use a marketable limit order. Set a limit a few ticks beyond the best price: above the ask for a buy, below the bid for a sell. It fills like a market order if the price holds and stops at your limit if it does not.
- Use the exchange’s protection. CME Globex handles market orders as market orders with protection: they fill at available prices up to a protection limit, and any remainder rests as a limit order. Slippage is capped, but a full fill is not guaranteed. Protection points vary by product.
- Check displayed depth before you trade. If your order is larger than the size within a tick or two of the best price, it will walk the book. A heatmap shows that depth in advance.
- Slice large orders. Splitting an order into smaller pieces over time reduces market impact, at the cost of exposure to price moves between pieces. For the impact of very large orders, see Bookmap’s guide to block trades and stock prices.
- Avoid scheduled events and thin sessions. Do not send market orders into FOMC, CPI or earnings releases, and take care in overnight sessions, when displayed depth is lower. Bookmap’s guide to reading the tape on low liquidity days covers those conditions.
- Be careful with stops. A stop-market order can fill far beyond the stop in a fast move. A stop-limit order caps the price but may not fill.
- Trade liquid instruments. Tighter spreads and deeper books mean less to walk. See Bookmap’s guide to evaluating stock liquidity.
Does Slippage Happen With Limit Orders?
Not in the usual negative sense. A limit order never fills at a price worse than its limit, so it has no negative slippage against that price. It can have positive slippage if it fills at a better price. What a limit order risks instead is not filling:
- The price may never reach your limit, so you miss the trade.
- The price may touch your limit and move away before your order fills, because orders ahead of you in the queue fill first.
- You may get only a partial fill.
The cost of a missed trade does not appear as slippage, but it is real. If you wanted the position and the market runs away, the missed move is an opportunity cost. Stop-limit orders carry the same risk: they can leave you in a losing trade when the price gaps through your limit. A marketable limit order, with the limit set beyond the best price, is a middle path.
How to Calculate Slippage Percentage in Day Trading
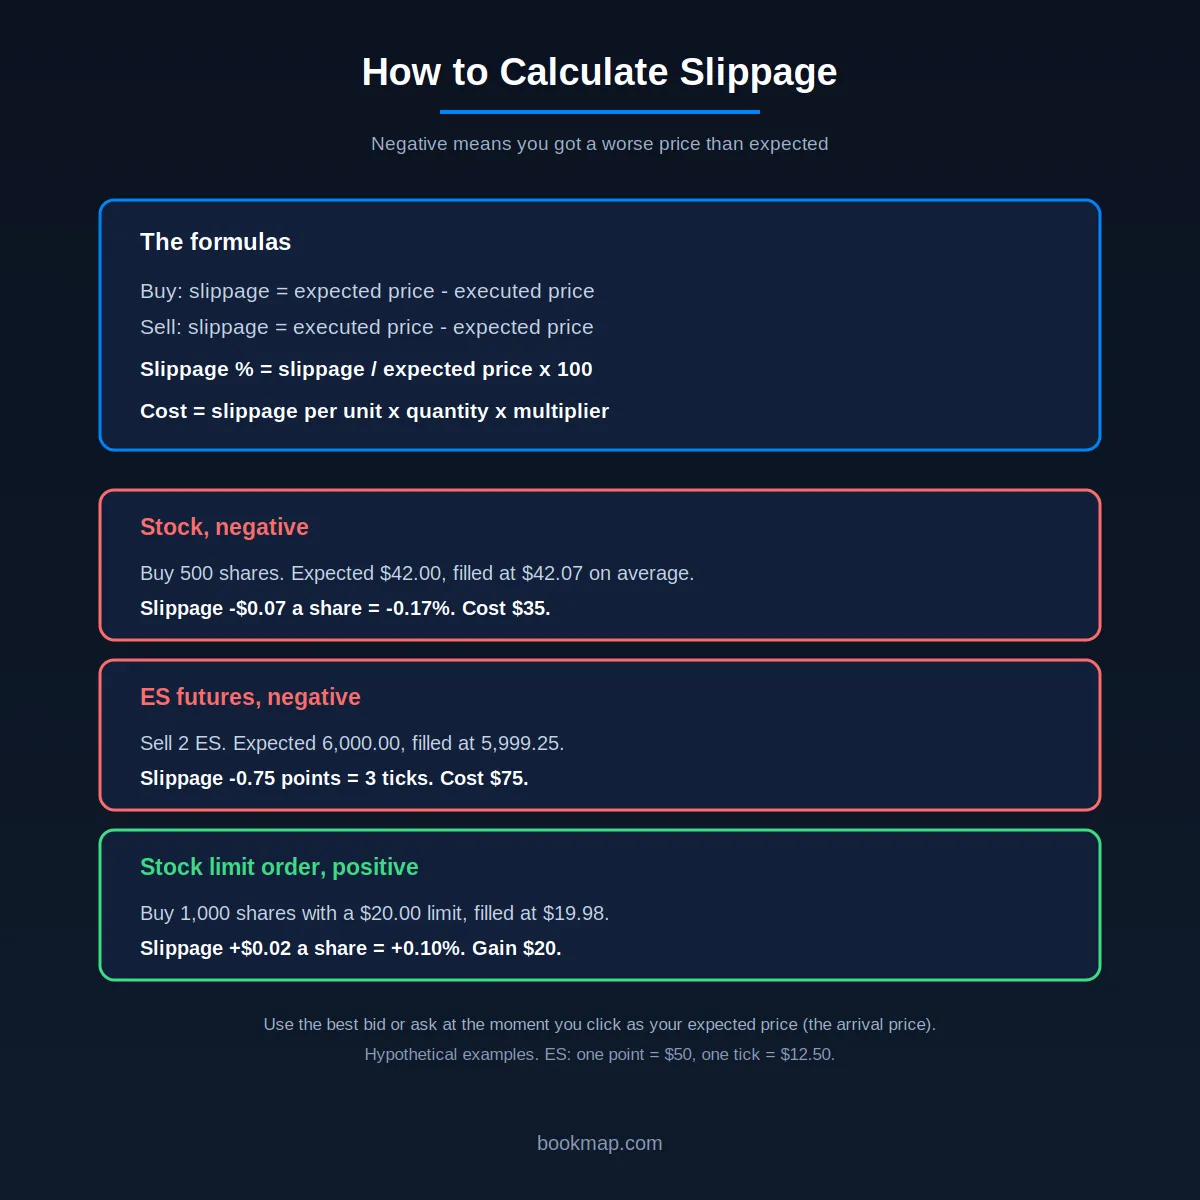
The formulas are simple:
- Buy: slippage = expected price minus executed price
- Sell: slippage = executed price minus expected price
- Slippage % = slippage divided by expected price, times 100
- Cost = slippage per unit, times quantity, times the contract multiplier for futures
A negative result means you got a worse price than expected. For a buy of 500 shares expected at $42.00 and filled at $42.07 on average, slippage is -$0.07 a share, or -0.17%, which costs $35.
In day trading, slippage matters because it repeats. Track it over many trades:
- Average slippage per trade, in ticks. This shows whether your execution is improving.
- Slippage as a share of average gross profit per trade. If a strategy earns an average of 4 ticks gross and loses 1 tick to slippage on entry and 1 tick on exit, slippage consumes half of the edge.
- Slippage by time of day and order type. This shows where it costs you most, such as market orders in the first minutes after the open.
To calculate it, you need the expected price, which most trade logs do not record. Log the best bid and ask at the moment you click, or use a platform that records it. For tick values by contract, see Bookmap’s guide to tick size, and for the day trading context, see day trading futures strategies.
How to Configure Slippage Tolerance in Your Platform
Where the setting lives depends on the market:
- Decentralized exchanges. The slippage tolerance field in the swap settings, set as a percentage. Stablecoin pairs can use a very tight tolerance. Volatile or thinly traded tokens need more room. Check price impact before confirming, and consider MEV protection.
- Forex and CFD platforms. Some platforms let you set a maximum price deviation on market orders, so the order is rejected if the price moves past it. MetaTrader calls this setting deviation, measured in points.
- Futures platforms. Control slippage with order type: market with protection, marketable limit orders or limit orders, and use the platform’s protection or maximum slippage options if it has them.
- Stock brokers. Use marketable limit orders with a cap, or limit-on-open and limit-on-close orders when trading the auctions.
General rules:
- Set tolerance relative to the instrument’s typical spread and volatility, not as a fixed number for every market.
- A setting that is too tight causes rejected or unfilled orders. One that is too loose invites bad fills.
- Test on small size first and review your fills.
For the order types behind these settings, see Bookmap’s guide to order types.
Slippage and Execution Quality
Slippage is one part of a larger question: how good were your fills? This section places it in that context.
Order Execution Quality Factors
Execution quality is how well an order is filled compared with what was available. The main factors:
- Price. How close the fill is to the best available price, including any price improvement.
- Speed. The time from order to fill.
- Likelihood of execution. Whether the order fills at all.
- Size. Whether the full quantity fills at the quoted price.
- Costs. Commissions, fees and rebates.
- Venue and routing. Where the order goes, which depends on the broker.
In US stocks, brokers and venues publish execution statistics under SEC Rule 605, which is being expanded for larger broker-dealers with a compliance date of August 1, 2026, and order routing reports under Rule 606. For how routing and payment arrangements affect fills, see Bookmap’s guide to payment for order flow.
Hidden Costs of Trading Financial Markets
Commissions are the cost you see. Others are easier to miss:
| Cost | Visible? | What it is |
| Commissions and fees | Yes | Per-trade or per-contract charges |
| Spread | Partly | The cost of crossing from bid to ask |
| Slippage | No | The difference between expected and executed price |
| Market impact | No | Price movement caused by your own order size |
| Opportunity cost | No | Profit missed when a limit order does not fill |
| Financing | Sometimes | Overnight interest on margin or leveraged positions |
For day traders, the hidden costs are often larger than the commissions. A strategy can show a profit before slippage and spread and a loss after them.
Market Microstructure and Transaction Cost Analysis
Professionals measure these costs with transaction cost analysis (TCA). It compares an execution with a benchmark:
- Arrival price. The market price when the order was submitted. This is the benchmark behind the slippage calculation above.
- VWAP. The volume-weighted average price over the period in which the order was worked.
- Implementation shortfall. The difference between the price when the trading decision was made and the final result, including costs and any part of the order that never filled.
- Effective spread. Twice the distance between the execution price and the midpoint of the quote when the order arrived. Comparing it with the quoted spread shows whether the order got price improvement.
Market microstructure explains why the numbers come out as they do: queue position, tick size, displayed and hidden depth, latency and where an order is routed. Retail traders can borrow the idea. Keep a log of expected price, fill price, size, order type and time, and review it monthly. For the structure behind it, see Bookmap’s guide to what has changed in market microstructure.
Conclusion
Slippage will happen to any trader at least once. It is an inevitable part of trading that cannot be totally eliminated but the chances of it happening can be reduced.
As a final note, new traders sometimes confuse slippage with spread. A trader must understand price differences in order to maximize profits and avoid losses. If you want to learn about the basics of this fundamental subject and how it applies to trading, check out this article on “What is a Spread in Financial Markets?
FAQs
What is slippage in trading?
Slippage is the difference between the price you expected when you placed an order and the price at which it executed. It can be negative (a worse price) or positive (a better price).
What causes slippage?
Two things: time and size. Prices can change between your click and the fill, and an order larger than the size available at the best price fills across several price levels.
What causes slippage in highly volatile markets?
Faster price movement, thinner order books as liquidity providers pull quotes, wider spreads, and surges of market orders from news, stop runs and liquidations.
How do I calculate slippage percentage?
For a buy, subtract the executed price from the expected price. For a sell, subtract the expected price from the executed price. Divide the result by the expected price and multiply by 100. A negative number means a worse price than expected.
Does slippage happen with limit orders?
Not negative slippage: a limit order fills at your limit price or better. It can have positive slippage. The risk is that the order does not fill, or fills only partly.
How do I prevent negative slippage on market orders?
Use marketable limit orders or the exchange’s protection, check displayed depth before you trade, slice large orders, avoid scheduled news and thin sessions, and be careful with stop-market orders.
What is positive slippage?
It is getting a better price than expected, for example when the price moves in your favor before the fill. It does not automatically offset negative slippage, and brokers handle it differently.
What is the difference between slippage and spread?
The spread is the gap between the best bid and best offer at one moment. Slippage is the gap between the price you expected and the price you got.
What is slippage tolerance on a decentralized exchange?
It is the maximum price deviation you will accept from the quote. It sets a minimum amount you must receive, and the swap reverts if the price moves past it. Too tight and swaps fail, too loose and bots can profit from your trade.
Does slippage happen in forex, and what about weekends?
Yes. Spreads widen around the daily rollover and news, and weekend gaps can open the market far from Friday’s close. Stop orders fill at the first available price in a gap, not at the stop price.
How does latency cause slippage?
By the time an order arrives at the matching engine, the quote it was based on may have moved. Faster participants can trade against slower participants’ stale quotes.
Sign Up Now
Latest Articles